Chapter XIX exclusion applies to payments received by the International Rice Research Institute, subject to specified privileges and immunities condit...
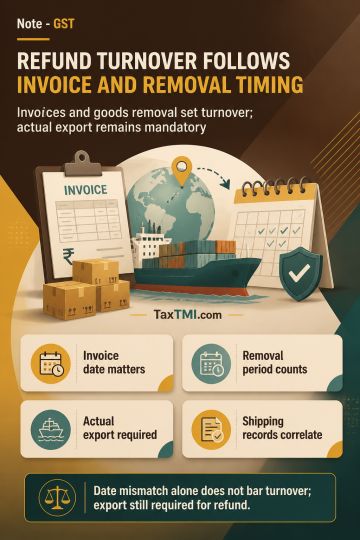
Rule 89(4) attributes the value of zero-rated goods to the refund period in which export invoices are issued and goods are removed under bond or LUT, rather than the later period of physical export. Sections 12 and 31 support invoice-and-removal recognition of supply, while actual export remains essential to establish export status and sustain the refund. Shipping bills and export records verify the later export event and must correlate with relevant invoices. Where export is delayed or does not occur within the stipulated period, Rule 96A governs extensions, tax and interest consequences; a mismatch in invoice and physical-export dates alone does not exclude the value from zero-rated turnover.
Rule 89(4) attributes the value of zero-rated goods to the refund period in which export invoices are issued and goods are removed under bond or LUT, rather than the later period of physical export. Sections 12 and 31 support invoice-and-removal recognition of supply, while actual export remains essential to establish export status and sustain the refund. Shipping bills and export records verify the later export event and must correlate with relevant invoices. Where export is delayed or does not occur within the stipulated period, Rule 96A governs extensions, tax and interest consequences; a mismatch in invoice and physical-export dates alone does not exclude the value from zero-rated turnover.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI