Jurisdictional sanction requirements bar reassessment when approval comes from an authority lacking statutory competence under the applicable framewor...
Recorded sales receipts cannot be reassessed as unexplained cash credits, eliminating the basis for consequential alleged commission expenditure addit...
Sufficient cause for delayed income-tax appeals requires bona fide diligence; unsubstantiated counsel illness and assessee inaction defeat condonation...
TNMM Segmentation Limits Transfer-Pricing Adjustments to Associated-Enterprise Transactions and Requires Turnover-Based Comparable Selection for IT Se...
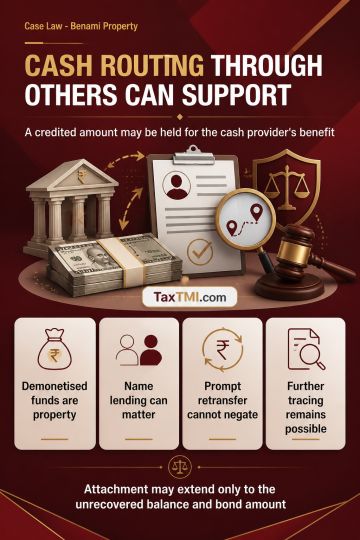
Demonetised cash qualifies as movable property for benami-law purposes. Where a person supplies cash to another person who deposits it in a proprietary bank account, lends their name, and retransfers the credited amount, the supplied cash may constitute consideration and the credited amount may constitute property held for the provider's benefit. Prompt retransfer does not negate the benami character. After tax remittance and deposit in an interest-free bond under the Pradhan Mantri Garib Kalyan Yojna, attachment may extend only to the unrecovered balance and bond amount; any unavailable balance may be traced through further investigation.
Demonetised cash qualifies as movable property for benami-law purposes. Where a person supplies cash to another person who deposits it in a proprietary bank account, lends their name, and retransfers the credited amount, the supplied cash may constitute consideration and the credited amount may constitute property held for the provider's benefit. Prompt retransfer does not negate the benami character. After tax remittance and deposit in an interest-free bond under the Pradhan Mantri Garib Kalyan Yojna, attachment may extend only to the unrecovered balance and bond amount; any unavailable balance may be traced through further investigation.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI