Survey surrender characterisation determines whether mixed excess stock and business-linked cash face normal taxation or special deemed-income taxatio...
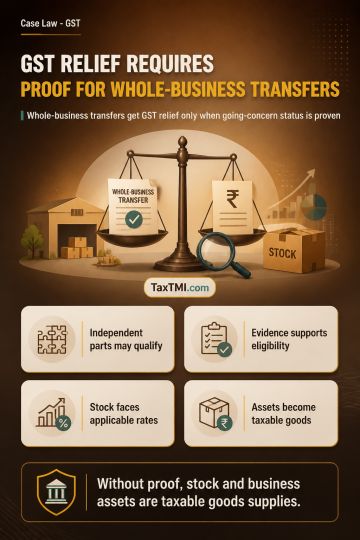
Transfer of an entire partnership business to a company without consideration may fall within GST supply, notwithstanding its occurrence outside the ordinary course of business. A transfer of a business undertaking as a going concern is classified as a supply of services rather than goods. The going-concern exemption applies only where the business, as a whole or independent part, satisfies that factual condition, requiring supporting evidence. If it does not qualify, the going-concern exception is unavailable and transferred stock and business assets are treated as taxable supplies of goods on cessation, at applicable rates.
Transfer of an entire partnership business to a company without consideration may fall within GST supply, notwithstanding its occurrence outside the ordinary course of business. A transfer of a business undertaking as a going concern is classified as a supply of services rather than goods. The going-concern exemption applies only where the business, as a whole or independent part, satisfies that factual condition, requiring supporting evidence. If it does not qualify, the going-concern exception is unavailable and transferred stock and business assets are treated as taxable supplies of goods on cessation, at applicable rates.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI