Own-account subcontracted services escape intermediary classification when suppliers perform substantive obligations rather than arrange another perso...
Restaurant business transfers qualify for GST exemption as going concerns when operations can continue independently despite retained past liabilities...
Voluntary customs statements and seizure evidence support penalties for attempted export of red sanders where alleged retractions remain unsubstantiat...
Page of 4960
Press 'Enter' after typing page number.
1 to 20 of 99183 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
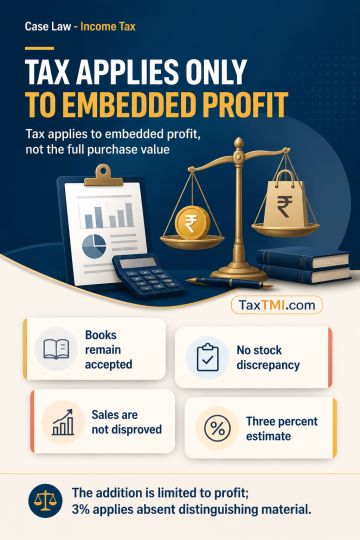
Embedded profit, rather than the entire value of alleged bogus diamond purchases, is taxable where books of account remain accepted, stock and quantitative records show no adverse discrepancy, and corresponding sales are not disproved. Where accommodation bills cover goods actually sourced from other parties, the addition should be confined to the profit arising from that arrangement. A 3% profit estimate applies where no distinguishing material warrants a different estimate, including for later assessment years involving identical transaction facts.
Embedded profit, rather than the entire value of alleged bogus diamond purchases, is taxable where books of account remain accepted, stock and quantitative records show no adverse discrepancy, and corresponding sales are not disproved. Where accommodation bills cover goods actually sourced from other parties, the addition should be confined to the profit arising from that arrangement. A 3% profit estimate applies where no distinguishing material warrants a different estimate, including for later assessment years involving identical transaction facts.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI




 Get Daily Updates