Own-account subcontracted services escape intermediary classification when suppliers perform substantive obligations rather than arrange another perso...
Restaurant business transfers qualify for GST exemption as going concerns when operations can continue independently despite retained past liabilities...
Voluntary customs statements and seizure evidence support penalties for attempted export of red sanders where alleged retractions remain unsubstantiat...
Page of 4960
Press 'Enter' after typing page number.
1 to 20 of 99183 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
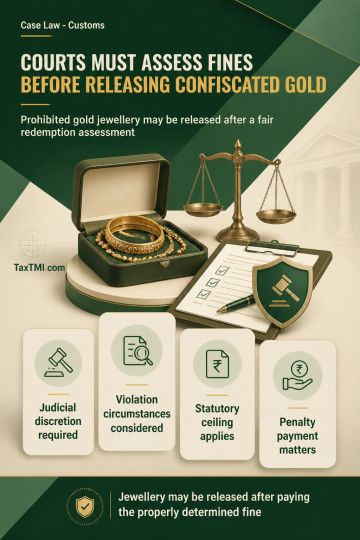
Redemption of confiscated prohibited goods under section 125 of the Customs Act is discretionary, but the discretion must be exercised judicially rather than denied mechanically because goods are prohibited. Redemption may require consideration of the circumstances of the violation, including the absence of serious or previous contraventions and payment of penalty. Redemption fine must remain within the statutory ceiling and be determined on the applicable principles. Upon payment of the properly determined fine, confiscated gold jewellery may be released.
Redemption of confiscated prohibited goods under section 125 of the Customs Act is discretionary, but the discretion must be exercised judicially rather than denied mechanically because goods are prohibited. Redemption may require consideration of the circumstances of the violation, including the absence of serious or previous contraventions and payment of penalty. Redemption fine must remain within the statutory ceiling and be determined on the applicable principles. Upon payment of the properly determined fine, confiscated gold jewellery may be released.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI




 Get Daily Updates