Capital-gains exemption for charitable trusts extends to qualifying fixed deposits, while unrecoverable TDS write-offs may constitute income applicati...
India-UK treaty characterisation of telecom-service receipts as business profits withstands unilateral domestic-law amendments for Indian tax purposes...
Page of 4868
Press 'Enter' after typing page number.
1 to 20 of 97343 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
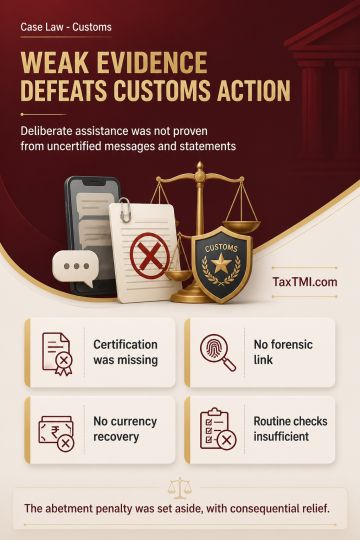
Electronic records relied on in customs penalty proceedings require prescribed certification, and an uncertified text-message printout has no evidentiary value where no forensic material links it to the alleged user. Such material cannot implicate a Customs officer in attempted illegal export of foreign currency. Abetment further requires proof of intentional aiding and active complicity; an uncorroborated co-noticee statement, absent recovery, CCTV, or independent-witness support, does not establish it. Failure to detect concealed currency during routine examination is insufficient. On these grounds, the penalty for abetment was set aside with consequential relief.
Electronic records relied on in customs penalty proceedings require prescribed certification, and an uncertified text-message printout has no evidentiary value where no forensic material links it to the alleged user. Such material cannot implicate a Customs officer in attempted illegal export of foreign currency. Abetment further requires proof of intentional aiding and active complicity; an uncorroborated co-noticee statement, absent recovery, CCTV, or independent-witness support, does not establish it. Failure to detect concealed currency during routine examination is insufficient. On these grounds, the penalty for abetment was set aside with consequential relief.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI