Government water works contract GST concession applied before its withdrawal, while contractual tax reimbursement claims lay outside advance-ruling sc...
Stamp valuation increases after registration-fee payment led to deletion of property-purchase addition within tolerance and without valuation referral...
The test of human probabilities permits tax authorities to look...
Human-probability test defeats political donation deduction where banking records mask accommodation-entry fund layering and evidence shows non-genuine contributions.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
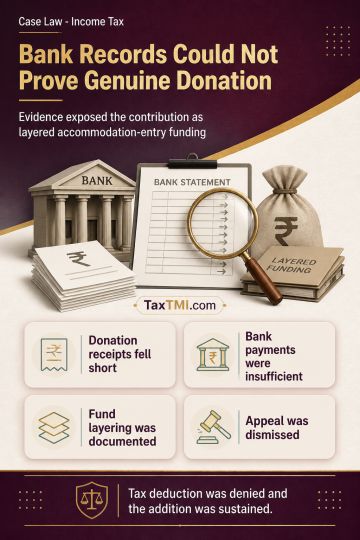
The test of human probabilities permits tax authorities to look beyond documentary evidence and banking-channel payments when assessing the real nature of a political contribution. Donation receipts and bank payments did not prove genuineness where investigation material, statements, bank-trail analysis, and the recipient party's modus operandi showed systematic fund layering for accommodation entries. The apparent transaction was not a genuine political contribution; the claimed deduction was denied, the consequential addition sustained, and the assessee's appeal dismissed.
The test of human probabilities permits tax authorities to look beyond documentary evidence and banking-channel payments when assessing the real nature of a political contribution. Donation receipts and bank payments did not prove genuineness where investigation material, statements, bank-trail analysis, and the recipient party's modus operandi showed systematic fund layering for accommodation entries. The apparent transaction was not a genuine political contribution; the claimed deduction was denied, the consequential addition sustained, and the assessee's appeal dismissed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI