Inter-terminal container movement requires customs escort, permit reconciliation, and indemnity, while delayed DPD cargo may move to designated CFS ya...
Year-wise GST tax periods make composite show cause notices impermissible, requiring separate proceedings despite contrary non-jurisdictional preceden...
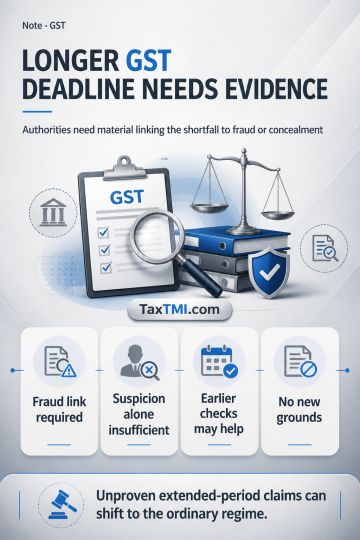
Section 74 CGST extended limitation applies only where available material permits a rational prima facie view that tax shortfall, erroneous refund or wrongful input tax credit arose by reason of fraud, wilful misstatement or suppression of facts to evade tax. Conclusive proof is not required at notice stage, but suspicion or a bare allegation is insufficient. Prior scrutiny, audit, inspection or pre-notice communications may supply the factual basis for a DRC-01 notice if they gave the taxpayer meaningful notice. Section 75 prevents confirmation on new grounds and permits treatment under the ordinary regime where the extended-period allegations are ultimately not established.
Section 74 CGST extended limitation applies only where available material permits a rational prima facie view that tax shortfall, erroneous refund or wrongful input tax credit arose by reason of fraud, wilful misstatement or suppression of facts to evade tax. Conclusive proof is not required at notice stage, but suspicion or a bare allegation is insufficient. Prior scrutiny, audit, inspection or pre-notice communications may supply the factual basis for a DRC-01 notice if they gave the taxpayer meaningful notice. Section 75 prevents confirmation on new grounds and permits treatment under the ordinary regime where the extended-period allegations are ultimately not established.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI