Fake-invoice penalties remain available where taxpayer admissions and records establish unsupported input tax credit claims and false GST documentatio...
Works contract classification applies to permanently installed fire-protection systems, while earthwork and obsolete IGST concessions remain unavailab...
Professional fee recovery for GST refund representation succeeds where direct engagement, fee acknowledgement, and authority are established despite c...
Transfer pricing of intra-group support services requires prescribed benchmarking; unsupported nil valuation and alternate business-expense disallowan...
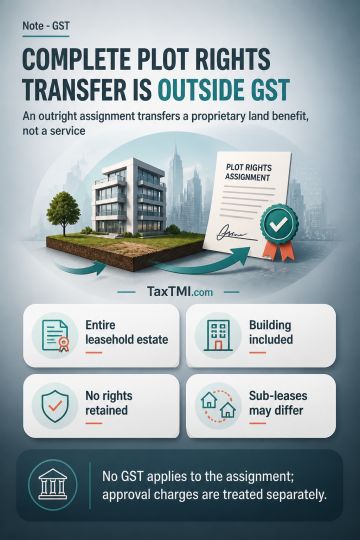
Outright assignment of an industrial lessee's entire leasehold estate, including the building, is distinguished from the original grant of a lease. Original leasing or renting is treated as a supply of services, but complete divestment without a retained reversionary interest transfers a proprietary benefit arising from land. Such a transfer falls within the Schedule III exclusion for land and specified building transactions, rather than service classification under Schedule II; GST charge therefore does not arise. Classification depends on the deed's substance, including rights retained, the assignee's assumption of lease covenants, and transferred structures. A sub-lease, licence, or continuing rental arrangement may be characterised differently. Approval charges collected by the industrial development corporation remain distinct from assignment consideration.
Outright assignment of an industrial lessee's entire leasehold estate, including the building, is distinguished from the original grant of a lease. Original leasing or renting is treated as a supply of services, but complete divestment without a retained reversionary interest transfers a proprietary benefit arising from land. Such a transfer falls within the Schedule III exclusion for land and specified building transactions, rather than service classification under Schedule II; GST charge therefore does not arise. Classification depends on the deed's substance, including rights retained, the assignee's assumption of lease covenants, and transferred structures. A sub-lease, licence, or continuing rental arrangement may be characterised differently. Approval charges collected by the industrial development corporation remain distinct from assignment consideration.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI