Separate speaking orders on reopening objections are mandatory; deciding them within reassessment invalidates jurisdiction and precludes revival of st...
Compulsorily convertible debentures remain debt before conversion, preventing transfer-pricing and interest-deduction disallowances on the stated fact...
Stock-in-trade transfer taxability follows possession and consideration, not later conveyance registration, limiting deemed-value provisions to the ac...
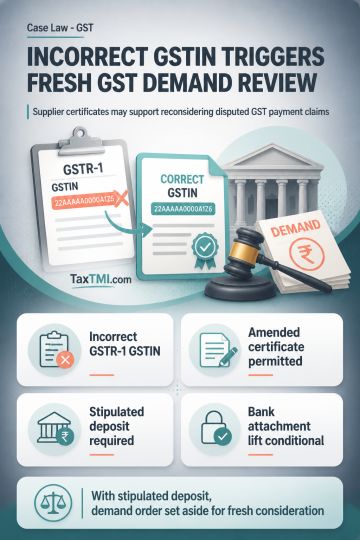
Supplier certification prima facie evidencing receipt of supplies and payment of GST may support reconsideration of a disputed GST demand despite an incorrect GSTIN being reported in GSTR-1. Where the certificate omitted the GSTIN of the person inadvertently recorded in GSTR-1, the taxpayer was permitted to submit an amended certificate identifying those particulars. Subject to the stipulated deposit, the demand order was set aside for fresh consideration after submission of the amended certificate, and the bank attachment was to be lifted upon compliance with that condition.
Supplier certification prima facie evidencing receipt of supplies and payment of GST may support reconsideration of a disputed GST demand despite an incorrect GSTIN being reported in GSTR-1. Where the certificate omitted the GSTIN of the person inadvertently recorded in GSTR-1, the taxpayer was permitted to submit an amended certificate identifying those particulars. Subject to the stipulated deposit, the demand order was set aside for fresh consideration after submission of the amended certificate, and the bank attachment was to be lifted upon compliance with that condition.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI