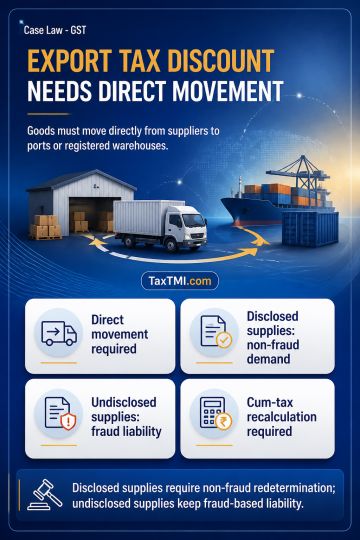
Merchant-export concessional GST rate requires direct movement of goods from the supplier to the export port or registered warehouse; movement through third-party distilleries does not satisfy the condition, notwithstanding actual export. For supplies disclosed through departmental intimations, incorrect availment of the concession alone did not establish fraud, wilful misstatement or suppression to evade tax, requiring redetermination as a non-fraud demand under Section 73(1). The fraud-based demand remained applicable to a supply for which no intimation was filed. Interest is compensatory and applies to tax ultimately determined as payable. Tax liability must be recomputed with cum-tax benefit under the CGST valuation rules.
Merchant-export concessional GST rate requires direct movement of goods from the supplier to the export port or registered warehouse; movement through third-party distilleries does not satisfy the condition, notwithstanding actual export. For supplies disclosed through departmental intimations, incorrect availment of the concession alone did not establish fraud, wilful misstatement or suppression to evade tax, requiring redetermination as a non-fraud demand under Section 73(1). The fraud-based demand remained applicable to a supply for which no intimation was filed. Interest is compensatory and applies to tax ultimately determined as payable. Tax liability must be recomputed with cum-tax benefit under the CGST valuation rules.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI