Jurisdictional sanction requirements bar reassessment when approval comes from an authority lacking statutory competence under the applicable framewor...
Recorded sales receipts cannot be reassessed as unexplained cash credits, eliminating the basis for consequential alleged commission expenditure addit...
Sufficient cause for delayed income-tax appeals requires bona fide diligence; unsubstantiated counsel illness and assessee inaction defeat condonation...
TNMM Segmentation Limits Transfer-Pricing Adjustments to Associated-Enterprise Transactions and Requires Turnover-Based Comparable Selection for IT Se...
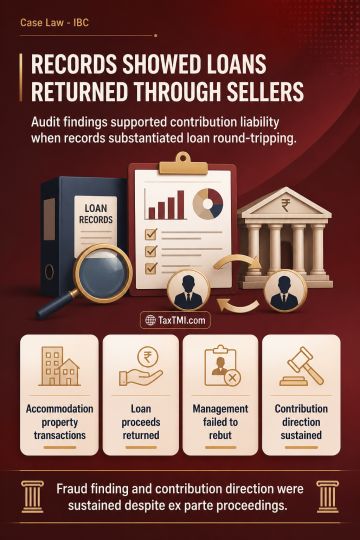
Forensic audit reports are not conclusive proof of fraud, but may support insolvency contribution liability when reliable documentary evidence substantiates their findings. Sale deeds, bank records, sub-registrar records and title-verification material supported findings that property transactions were accommodation arrangements used to raise loans. Loan proceeds substantially returned through sellers to the corporate debtor and related entities, establishing round-tripping intended to defraud creditors. Former management failed to rebut matters within its special knowledge. Ex parte determination remained valid because suspended directors received adequate opportunity to contest the proceedings and did not produce reliable contrary material. The fraudulent-transaction finding and consequential contribution direction were sustained.
Forensic audit reports are not conclusive proof of fraud, but may support insolvency contribution liability when reliable documentary evidence substantiates their findings. Sale deeds, bank records, sub-registrar records and title-verification material supported findings that property transactions were accommodation arrangements used to raise loans. Loan proceeds substantially returned through sellers to the corporate debtor and related entities, establishing round-tripping intended to defraud creditors. Former management failed to rebut matters within its special knowledge. Ex parte determination remained valid because suspended directors received adequate opportunity to contest the proceedings and did not produce reliable contrary material. The fraudulent-transaction finding and consequential contribution direction were sustained.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI