Jurisdictional sanction requirements bar reassessment when approval comes from an authority lacking statutory competence under the applicable framewor...
Recorded sales receipts cannot be reassessed as unexplained cash credits, eliminating the basis for consequential alleged commission expenditure addit...
Sufficient cause for delayed income-tax appeals requires bona fide diligence; unsubstantiated counsel illness and assessee inaction defeat condonation...
TNMM Segmentation Limits Transfer-Pricing Adjustments to Associated-Enterprise Transactions and Requires Turnover-Based Comparable Selection for IT Se...
Internal TNMM supports deletion of freight-forwarding adjustments where comparable non-AE transactions are separately identifiable and materially simi...
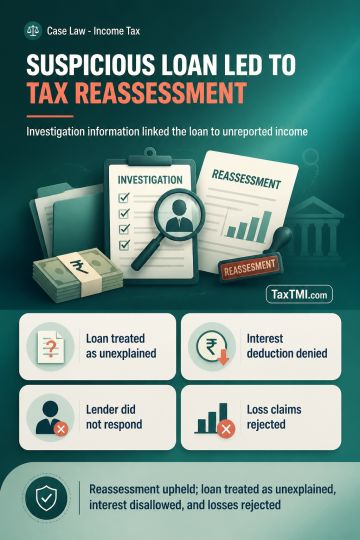
Specific investigation information linking an unsecured loan to an alleged accommodation-entry lender can establish a live nexus for reassessment; conclusive proof of escaped income is not required when reasons are recorded. Reassessment was upheld on that basis. Confirmation and banking records alone do not establish an unsecured loan's creditworthiness or genuineness where the lender does not respond to statutory notice, is not produced for examination, and adverse investigation material remains unrebutted. The loan was treated as unexplained cash credit and related interest was disallowed. Business-loss set-off and carry-forward require sufficient material demonstrating compliance with statutory conditions; unsupported current-year and brought-forward loss claims were rejected.
Specific investigation information linking an unsecured loan to an alleged accommodation-entry lender can establish a live nexus for reassessment; conclusive proof of escaped income is not required when reasons are recorded. Reassessment was upheld on that basis. Confirmation and banking records alone do not establish an unsecured loan's creditworthiness or genuineness where the lender does not respond to statutory notice, is not produced for examination, and adverse investigation material remains unrebutted. The loan was treated as unexplained cash credit and related interest was disallowed. Business-loss set-off and carry-forward require sufficient material demonstrating compliance with statutory conditions; unsupported current-year and brought-forward loss claims were rejected.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI