Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
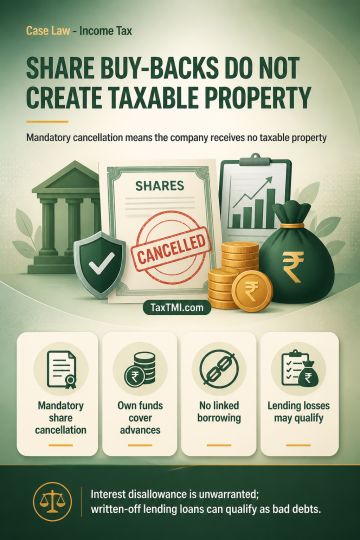
Buy-back of a company's own shares followed by mandatory extinguishment does not entail receipt of "property" for section 56(2)(x), because the shares cannot be held, enjoyed or transferred by the company as an asset. Interest-free advances do not justify interest disallowance under section 36(1)(iii) where interest-free own funds exceed those advances and no specific borrowing is traceable to them; proportionate disallowance from a mixed pool of funds is unwarranted. Principal loans and inter-corporate deposits written off in an organised money-lending business qualify as bad debts where actual write-off occurs. A lending licence, tax-audit description and the proportion of interest income are not determinative of that business character.
Buy-back of a company's own shares followed by mandatory extinguishment does not entail receipt of "property" for section 56(2)(x), because the shares cannot be held, enjoyed or transferred by the company as an asset. Interest-free advances do not justify interest disallowance under section 36(1)(iii) where interest-free own funds exceed those advances and no specific borrowing is traceable to them; proportionate disallowance from a mixed pool of funds is unwarranted. Principal loans and inter-corporate deposits written off in an organised money-lending business qualify as bad debts where actual write-off occurs. A lending licence, tax-audit description and the proportion of interest income are not determinative of that business character.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI