Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ Call / WhatsApp at: +91 99117 96707

For more information, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws---- ❯
  • ---- All Laws----
  • Income Tax
  • Direct Taxes
  • Benami Property
  • Central GST Laws
  • SGST - State GST Laws
  • Customs
  • FTP - Foreign Trade Policy
  • SEZ - Special Economic Zone
  • FEMA - Foreign Exchange Management
  • Companies Law
  • SEBI - Securities & Exchange Board of India
  • IBC - Insolvency and Bankruptcy
  • Law of Competition
  • PMLA - Money-Laundering
  • Indian Laws
  • Bill / Finance Bills
  • Wealth Tax
  • Service Tax
  • Central Excise
  • VAT / Sales Tax
Month:
---- All Months ---- ❯
  • ---- All Months ----
  • January
  • February
  • March
  • April
  • May
  • June
  • July
  • August
  • September
  • October
  • November
  • December
Year:
---- All Years ---- ❯
  • ---- All Years ----
  • 2026
  • 2025
  • 2024
  • 2023
  • 2022
  • 2021
  • 2020
  • 2019
  • 2018
  • 2017
  • 2016
  • 2015
  • 2014
  • 2013
  • 2012
  • 2011
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
☰   Show Results ❯
    Limitation for Revenue refund appeals begins when the order is issued, barring delayed departmental challenges beyond condonable time.
    Survey surrender characterisation determines whether mixed excess stock and business-linked cash face normal taxation or special deemed-income taxatio...
    GST seizure retention limits require return of phones and debit cards when no valid extension order exists.
    Functional integration of dedicated analytical cartridges overrides residual plastics classification, placing specialised coagulation micro-cuvettes w...
    Speaking appellate orders in GST appeals require findings on material grounds and reasons, preserving meaningful review and procedural fairness.
    Pre-movement e-way bill compliance makes post-interception documents insufficient to cure undocumented goods transport and potential detention.
    Special Notified Zone rules now permit eligible foreign rough-diamond entities to import, sell, auction and re-export diamonds.
    Penalty waiver applications now require prescribed payment details and an undertaking not to appeal the assessment order.
    Securities-law settlement framework introduces formula-based terms, fast-track routes, confidentiality incentives, and revocation for non-compliance i...
    EU sugar tariff-rate quota allocation sets export conditions, certification and reporting requirements for India's preferential sugar exports.
    Sea Arrival Manifest amendments require a pre-existing Cargo Summary Notification and follow different approval paths before and after Entry Inwards.
    SCMTR manifest amendments require prescribed SCA or SAA messages, with approval required for post-Sea Entry Inwards changes.
    Project import finalisation requires complete closure documents within the special window, or customs recovery and penalty action may follow.
    Baryte export controls require licensing for Grade A and Grade B, while declared CDW consignments face gravity testing.
    RoDTEP ineligibility for DFIA exports requires repayment of wrongly claimed rebates with interest and may trigger customs recovery proceedings.
    Inter-CFS export cargo transfers after Let Export Order may proceed without escort when secured by verified Customs Bottle Seals.
    Intent to evade tax required for detention penalty where unamended law linked e-way bill breaches to confiscation.
    Custodial interrogation requires individualised necessity; documentary GST credit allegations alone did not preclude conditional anticipatory bail.
    GST detention penalties require hearings, cannot exceed show-cause notices, and do not arise merely from lawful batch transportation.
    Input tax credit requires proof that suppliers paid tax, while interest applies only to credit availed and utilised.
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Highlights
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries

Highlights

Back

All Highlights

Showing Results for :
Reset Filters
No Records Found

Highlights

Back

All Highlights

Pre-institution mediation under Section 12A is mandatory for...

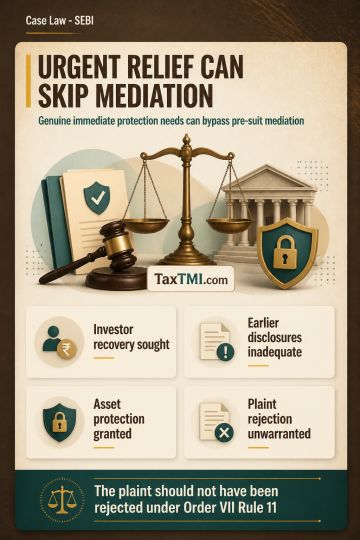
Urgent interim relief exception permits commercial suit without pre-institution mediation where immediate disclosure and asset protection are genuinely required.

Contents
Summary
Note

Note

-

Bookmark

Print

Print

SEBI August 25, 2026 Case Laws HC
Pre-institution mediation under Section 12A is mandatory for commercial suits that do not contemplate urgent interim relief. Whether the exception applies must be assessed from the plaintiff's standpoint, considering the suit's nature, cause of action and pleaded need for immediate protection; an unfounded urgency plea cannot bypass mediation. Urgent relief was genuinely contemplated where the suit sought investor recovery, earlier disclosures were inadequate, and ad-interim disclosure and asset-protection measures had already been granted despite existing regulatory restraints. The subsequent delay objection failed because investor claims had to be received before institution. Pre-institution mediation was therefore not a condition precedent, and rejection of the plaint under Order VII Rule 11 was unwarranted.

Topics

Acts Income Tax





















