Blocked input tax credit for resort construction remains unavailable; interest follows actual utilisation, while delayed payment attracts statutory pe...
Duplicate PAN allocation requires record verification and deactivation reasons before assessment-related transactions can be attributed to an assessee...
Faceless assessment safeguards require requested personal hearings and adequate final show-cause response time, failing which reassessment is required...
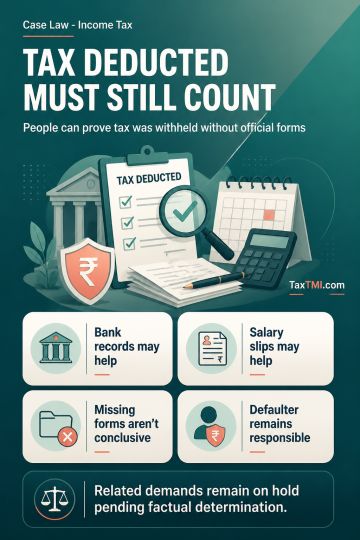
TDS credit must be considered where tax was actually deducted from a deductee's income or payment but was not remitted by the deductor. The statutory bar on recovering such tax from the deductee operates once actual deduction is established, preventing double recovery while permitting action against the defaulting deductor. Absence of Form 16, Form 16A or Form 26AS is not conclusive where the deductor has failed to deposit or report TDS. Deductees may rely on cogent evidence, including salary slips, bank records, invoices, payment advices, ledgers, correspondence or insolvency claims. Prima facie claims require factual verification rather than mechanical rejection, with related demands kept in abeyance pending determination.
TDS credit must be considered where tax was actually deducted from a deductee's income or payment but was not remitted by the deductor. The statutory bar on recovering such tax from the deductee operates once actual deduction is established, preventing double recovery while permitting action against the defaulting deductor. Absence of Form 16, Form 16A or Form 26AS is not conclusive where the deductor has failed to deposit or report TDS. Deductees may rely on cogent evidence, including salary slips, bank records, invoices, payment advices, ledgers, correspondence or insolvency claims. Prima facie claims require factual verification rather than mechanical rejection, with related demands kept in abeyance pending determination.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI