Ratification of resignation acceptance validates separation retrospectively, while withdrawal may be refused through reasoned administrative discretio...
Nature-dependent electricity contracts receive new Ind AS accounting, hedge designation, transition and financial-statement disclosure requirements fr...
Alternative GST remedy permitted protective writ intervention for ex parte adjudication, preserving independent appellate review of input tax credit d...
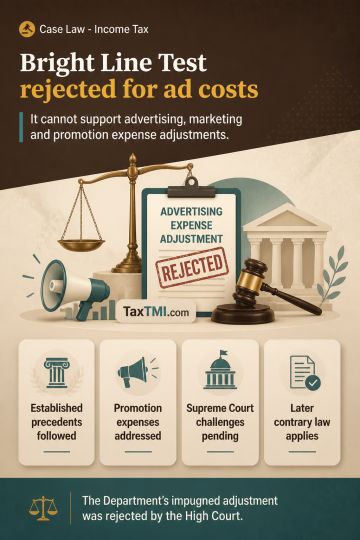
Bright Line Test is not a legally sanctioned method for transfer pricing adjustments relating to advertising, marketing and promotion expenses. Following the established position in Sony Ericsson and Maruti Suzuki, the High Court rejected the Department's use of that test for the impugned adjustment. The pendency of challenges to those precedents before the Supreme Court did not justify a different approach, although any contrary law subsequently declared in those proceedings would apply correspondingly.
Bright Line Test is not a legally sanctioned method for transfer pricing adjustments relating to advertising, marketing and promotion expenses. Following the established position in Sony Ericsson and Maruti Suzuki, the High Court rejected the Department's use of that test for the impugned adjustment. The pendency of challenges to those precedents before the Supreme Court did not justify a different approach, although any contrary law subsequently declared in those proceedings would apply correspondingly.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4897