Personal liberty safeguards restrict arrest after court-directed GST appearance, requiring interim release where authorities overreach pending proceed...
Alternative statutory remedy and delay bar GST writ challenges despite pending rectification, while distinct subject matter permits parallel proceedin...
Unverified Insight Portal Information Cannot Justify Reassessment Without a Verified Taxpayer-Specific Income-Escape Nexus or Demonstrated Application...
Assessing Officer jurisdiction after statutory transfer invalidates reassessment notices issued by transferor officers and nullifies resulting proceed...
Consequential appeal-effect orders must implement rectification deleting working-capital adjustments and reconsider the resulting arm's-length range c...
Discounted cash flow valuation protects share premium where projections are reasonable, while audited book expenses defeat unexplained-expenditure add...
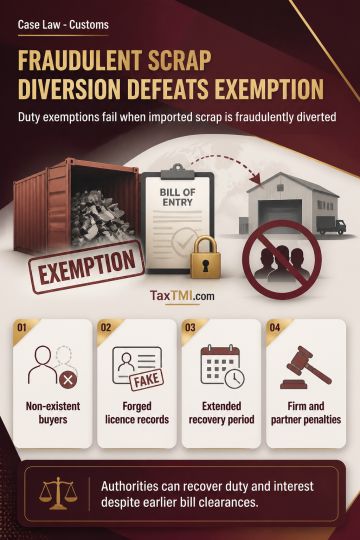
Fraudulent diversion of duty-free SEZ scrap into the DTA vitiates advance-licence exemption, permits recovery of customs and central excise duty with interest, and supports invocation of the extended limitation period. Non-existent buyers, forged, cancelled or suspended licence documentation, and cash-funded payment arrangements establish fraudulent availment where goods were neither received by stated recipients nor used to meet export obligations. Recovery proceedings for duty not levied or short-levied remain available despite prior assessment and clearance of bills of entry. DRI-issued show-cause notices and adjudication by the Commissioner of Customs are valid under the statutory jurisdictional position. Segregating and processing mixed imported scrap into distinct marketable copper and brass scrap constitutes manufacture. Penalties may concurrently apply to a partnership firm and an active partner who participated in the diversion.
Fraudulent diversion of duty-free SEZ scrap into the DTA vitiates advance-licence exemption, permits recovery of customs and central excise duty with interest, and supports invocation of the extended limitation period. Non-existent buyers, forged, cancelled or suspended licence documentation, and cash-funded payment arrangements establish fraudulent availment where goods were neither received by stated recipients nor used to meet export obligations. Recovery proceedings for duty not levied or short-levied remain available despite prior assessment and clearance of bills of entry. DRI-issued show-cause notices and adjudication by the Commissioner of Customs are valid under the statutory jurisdictional position. Segregating and processing mixed imported scrap into distinct marketable copper and brass scrap constitutes manufacture. Penalties may concurrently apply to a partnership firm and an active partner who participated in the diversion.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI