Section 115BBE classification requires a valid deeming-provision basis before special taxation, while the enhanced rate's temporal application remains...
Coercive recovery during GST searches is restrained pending scrutiny, preserving normal business operations and requiring adherence to investigation g...
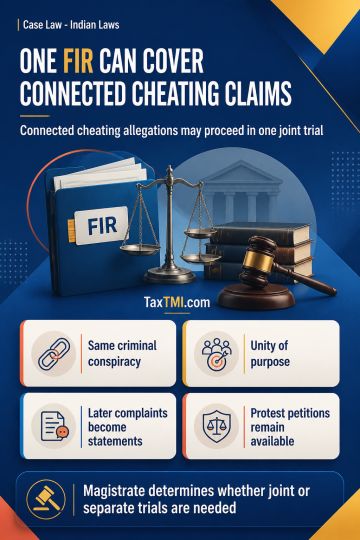
A single FIR may cover multiple allegations of cheating arising from one criminal conspiracy where the information concerns the same cognizable offence, occurrence or connected transaction; later complaints may be treated as witness statements during investigation. Whether offences form the same transaction depends on unity of purpose and design, proximity of time and place, and continuity of action, and these considerations are not cumulative. The Magistrate must assess the investigation material to decide whether connected cheating allegations warrant joint charges and trial or require separate trials. Complainants treated as witnesses may file protest petitions against closure reports or proposed discharge.
A single FIR may cover multiple allegations of cheating arising from one criminal conspiracy where the information concerns the same cognizable offence, occurrence or connected transaction; later complaints may be treated as witness statements during investigation. Whether offences form the same transaction depends on unity of purpose and design, proximity of time and place, and continuity of action, and these considerations are not cumulative. The Magistrate must assess the investigation material to decide whether connected cheating allegations warrant joint charges and trial or require separate trials. Complainants treated as witnesses may file protest petitions against closure reports or proposed discharge.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI