Fake-invoice penalties remain available where taxpayer admissions and records establish unsupported input tax credit claims and false GST documentatio...
Works contract classification applies to permanently installed fire-protection systems, while earthwork and obsolete IGST concessions remain unavailab...
Professional fee recovery for GST refund representation succeeds where direct engagement, fee acknowledgement, and authority are established despite c...
Transfer pricing of intra-group support services requires prescribed benchmarking; unsupported nil valuation and alternate business-expense disallowan...
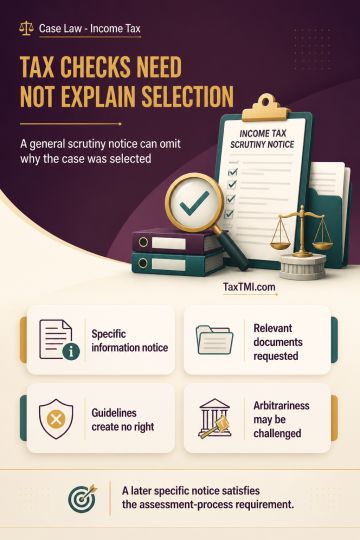
A scrutiny notice under section 143(2) merely informs the assessee that the case has been selected for scrutiny and need not disclose the selection reasons or scope of scrutiny. CBDT and departmental selection guidelines are described as inter-departmental instructions that do not create an assessee right to demand those reasons. Selection may be challenged only on proof of arbitrariness or vendetta. During assessment, the Assessing Officer must issue a specific notice seeking relevant information and documents; the notes state that such a subsequent notice satisfies the assessment-process requirement.
A scrutiny notice under section 143(2) merely informs the assessee that the case has been selected for scrutiny and need not disclose the selection reasons or scope of scrutiny. CBDT and departmental selection guidelines are described as inter-departmental instructions that do not create an assessee right to demand those reasons. Selection may be challenged only on proof of arbitrariness or vendetta. During assessment, the Assessing Officer must issue a specific notice seeking relevant information and documents; the notes state that such a subsequent notice satisfies the assessment-process requirement.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI