Fake-invoice penalties remain available where taxpayer admissions and records establish unsupported input tax credit claims and false GST documentatio...
Works contract classification applies to permanently installed fire-protection systems, while earthwork and obsolete IGST concessions remain unavailab...
Professional fee recovery for GST refund representation succeeds where direct engagement, fee acknowledgement, and authority are established despite c...
Transfer pricing of intra-group support services requires prescribed benchmarking; unsupported nil valuation and alternate business-expense disallowan...
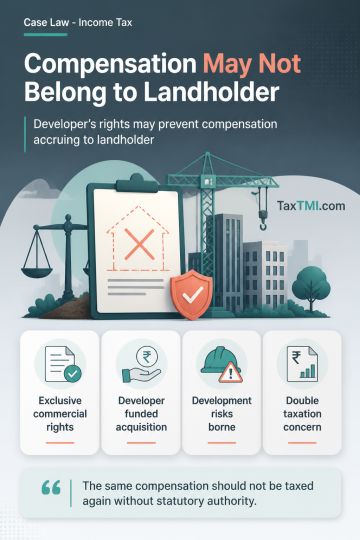
Compulsory-acquisition compensation attributable to development rights transferred under a pre-existing development agreement is discussed as not accruing to the land-holding company where the developer held exclusive commercial rights, funded the acquisition, and bore development risks. The notes distinguish an overriding contractual obligation from an application of income after accrual. They further state that taxing the same transferred compensation again in the land-holder's hands, after its taxation in the developer's hands, would create impermissible double taxation without statutory authority. Consistent treatment is also identified as relevant where materially identical development arrangements have received different tax treatment.
Compulsory-acquisition compensation attributable to development rights transferred under a pre-existing development agreement is discussed as not accruing to the land-holding company where the developer held exclusive commercial rights, funded the acquisition, and bore development risks. The notes distinguish an overriding contractual obligation from an application of income after accrual. They further state that taxing the same transferred compensation again in the land-holder's hands, after its taxation in the developer's hands, would create impermissible double taxation without statutory authority. Consistent treatment is also identified as relevant where materially identical development arrangements have received different tax treatment.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI