Faceless assessment and registration procedures are updated through electronic communication, revised recovery rules, extended deadlines, and replacem...
Risk-based selective vessel boarding requires accurate declarations and preserves master and agent liability where physical inspections are not select...
Permanent-establishment reassessment cannot revisit scrutinised disclosures; extended reopening fails without undisclosed material facts and within st...
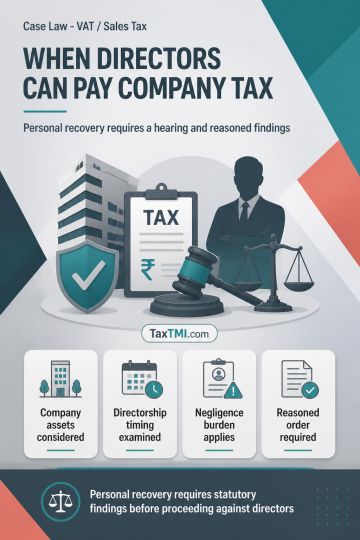
Section 39 permits personal recovery of a company's tax dues from a Director only after considering the availability of company assets, whether the person was a Director when the dues arose, and whether non-recovery resulted from negligence, misfeasance or breach of duty. The Director bears the statutory burden of establishing that non-recovery was not attributable to such conduct. Recovery from personal assets requires a hearing and a reasoned order on these matters, while recovery may first be pursued against company assets and subsequently against Directors under the statutory scheme.
Section 39 permits personal recovery of a company's tax dues from a Director only after considering the availability of company assets, whether the person was a Director when the dues arose, and whether non-recovery resulted from negligence, misfeasance or breach of duty. The Director bears the statutory burden of establishing that non-recovery was not attributable to such conduct. Recovery from personal assets requires a hearing and a reasoned order on these matters, while recovery may first be pursued against company assets and subsequently against Directors under the statutory scheme.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI