Faceless assessment and registration procedures are updated through electronic communication, revised recovery rules, extended deadlines, and replacem...
Risk-based selective vessel boarding requires accurate declarations and preserves master and agent liability where physical inspections are not select...
Permanent-establishment reassessment cannot revisit scrutinised disclosures; extended reopening fails without undisclosed material facts and within st...
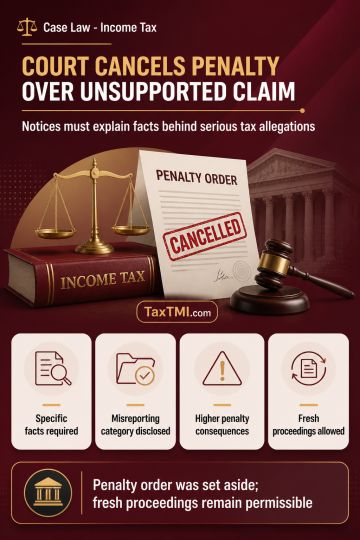
For penalty proceedings under section 270A, a show cause notice alleging misreporting must disclose the specific factual basis and category of misreporting so the taxpayer can respond meaningfully. Misreporting is treated as under-reporting involving bad faith, attracts a higher penalty, and precludes immunity; therefore, a bare allegation is insufficient. The notes state that notices and the penalty order merely asserted misreporting without particulars or reasons, and that the tax sought to be evaded required reconsideration. The High Court set aside the penalty order as unsustainable, while permitting fresh proceedings in accordance with law and leaving all contentions open.
For penalty proceedings under section 270A, a show cause notice alleging misreporting must disclose the specific factual basis and category of misreporting so the taxpayer can respond meaningfully. Misreporting is treated as under-reporting involving bad faith, attracts a higher penalty, and precludes immunity; therefore, a bare allegation is insufficient. The notes state that notices and the penalty order merely asserted misreporting without particulars or reasons, and that the tax sought to be evaded required reconsideration. The High Court set aside the penalty order as unsustainable, while permitting fresh proceedings in accordance with law and leaving all contentions open.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI