Fake-invoice penalties remain available where taxpayer admissions and records establish unsupported input tax credit claims and false GST documentatio...
Works contract classification applies to permanently installed fire-protection systems, while earthwork and obsolete IGST concessions remain unavailab...
Professional fee recovery for GST refund representation succeeds where direct engagement, fee acknowledgement, and authority are established despite c...
Transfer pricing of intra-group support services requires prescribed benchmarking; unsupported nil valuation and alternate business-expense disallowan...
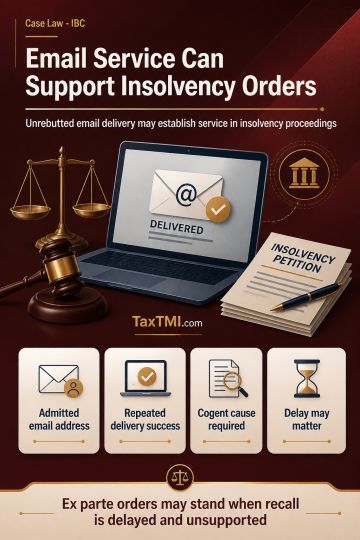
Service of notice through an admitted email address may support a presumption of service where repeated communications do not bounce and the presumption remains unrebutted. The notes address recall of an ex parte insolvency order, stressing that parties must show cogent sufficient cause for non-appearance and a substantial delay in seeking recall. In time-bound IBC proceedings, unexplained delay may not be condoned or disregarded. The absence of fraud or misrepresentation is also relevant when challenging an ex parte order.
Service of notice through an admitted email address may support a presumption of service where repeated communications do not bounce and the presumption remains unrebutted. The notes address recall of an ex parte insolvency order, stressing that parties must show cogent sufficient cause for non-appearance and a substantial delay in seeking recall. In time-bound IBC proceedings, unexplained delay may not be condoned or disregarded. The absence of fraud or misrepresentation is also relevant when challenging an ex parte order.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI