Territorial jurisdiction in income-tax appeals follows the assessing officer's location, not the Tribunal's seat or a subsequent acquirer's registered...
Transfer pricing comparables must reflect functional similarity, with diverse activities and asset profiles supporting exclusion from contract service...
Real income in electricity distribution excludes surcharges and regulatory assets without reasonably certain recovery, while deductions require return...
Contempt for company bank account restraint breaches requires deliberate disobedience, while contempt appeals are limited to orders imposing punishmen...
Page of 4947
Press 'Enter' after typing page number.
21 to 40 of 98935 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
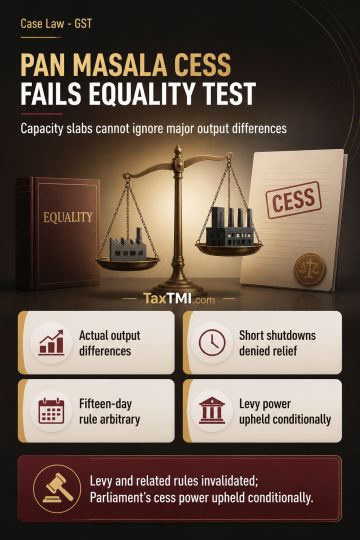
Capacity-based cess on pan masala packing machines was examined against Article 14 because the levy charged identical cess within a capacity slab despite substantial differences in actual output. The article states that deeming production, rather than taxing actual production, lacked rational classification and created manifest inequality; the capacity-based levy, related Rules and consequential notifications were therefore invalidated to that extent. It also notes that restricting abatement to continuous machine non-operation of at least fifteen days was arbitrary because genuine shorter shutdowns received no relief. Parliament's residuary power to levy cess on ownership or possession of machines was upheld, subject to constitutional equality requirements.
Capacity-based cess on pan masala packing machines was examined against Article 14 because the levy charged identical cess within a capacity slab despite substantial differences in actual output. The article states that deeming production, rather than taxing actual production, lacked rational classification and created manifest inequality; the capacity-based levy, related Rules and consequential notifications were therefore invalidated to that extent. It also notes that restricting abatement to continuous machine non-operation of at least fifteen days was arbitrary because genuine shorter shutdowns received no relief. Parliament's residuary power to levy cess on ownership or possession of machines was upheld, subject to constitutional equality requirements.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4947




 Get Daily Updates