Cross-border secondment reimbursements require separate employment and knowledge-transfer analysis before taxation as included services under the Indi...
Customs procedure uniformity requires adoption of model clearance practices, subject to specific local requirements and infrastructure or geographical...
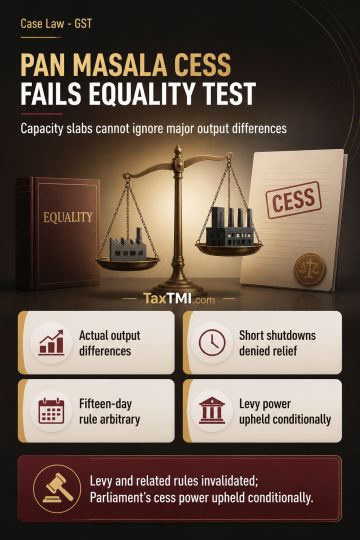
Capacity-based cess on pan masala packing machines was examined against Article 14 because the levy charged identical cess within a capacity slab despite substantial differences in actual output. The article states that deeming production, rather than taxing actual production, lacked rational classification and created manifest inequality; the capacity-based levy, related Rules and consequential notifications were therefore invalidated to that extent. It also notes that restricting abatement to continuous machine non-operation of at least fifteen days was arbitrary because genuine shorter shutdowns received no relief. Parliament's residuary power to levy cess on ownership or possession of machines was upheld, subject to constitutional equality requirements.
Capacity-based cess on pan masala packing machines was examined against Article 14 because the levy charged identical cess within a capacity slab despite substantial differences in actual output. The article states that deeming production, rather than taxing actual production, lacked rational classification and created manifest inequality; the capacity-based levy, related Rules and consequential notifications were therefore invalidated to that extent. It also notes that restricting abatement to continuous machine non-operation of at least fifteen days was arbitrary because genuine shorter shutdowns received no relief. Parliament's residuary power to levy cess on ownership or possession of machines was upheld, subject to constitutional equality requirements.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI


 Get Daily Updates