Faceless assessment and registration procedures are updated through electronic communication, revised recovery rules, extended deadlines, and replacem...
Risk-based selective vessel boarding requires accurate declarations and preserves master and agent liability where physical inspections are not select...
Permanent-establishment reassessment cannot revisit scrutinised disclosures; extended reopening fails without undisclosed material facts and within st...
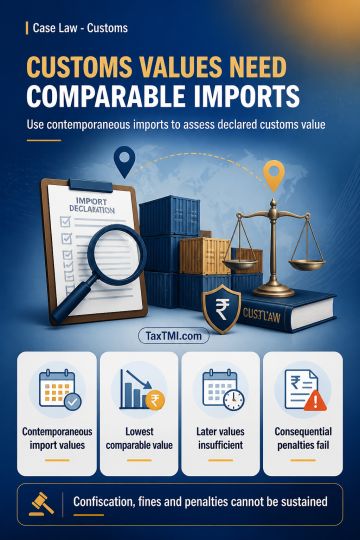
Customs valuation must consider contemporaneous import values and adopt the lowest comparable transaction value under Rule 5(3) of the Customs Valuation Rules, 2007. The notes state that reliance on a later-period import value, without addressing comparable imports close to the declared price or complying with remand directions, cannot support enhancement of declared value. They further explain that where the undervaluation finding and differential-duty demand fail, consequential confiscation, redemption fine and penalties, including penalties on co-noticee partners absent independent grounds, cannot be sustained.
Customs valuation must consider contemporaneous import values and adopt the lowest comparable transaction value under Rule 5(3) of the Customs Valuation Rules, 2007. The notes state that reliance on a later-period import value, without addressing comparable imports close to the declared price or complying with remand directions, cannot support enhancement of declared value. They further explain that where the undervaluation finding and differential-duty demand fail, consequential confiscation, redemption fine and penalties, including penalties on co-noticee partners absent independent grounds, cannot be sustained.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI