Faceless assessment and registration procedures are updated through electronic communication, revised recovery rules, extended deadlines, and replacem...
Risk-based selective vessel boarding requires accurate declarations and preserves master and agent liability where physical inspections are not select...
Permanent-establishment reassessment cannot revisit scrutinised disclosures; extended reopening fails without undisclosed material facts and within st...
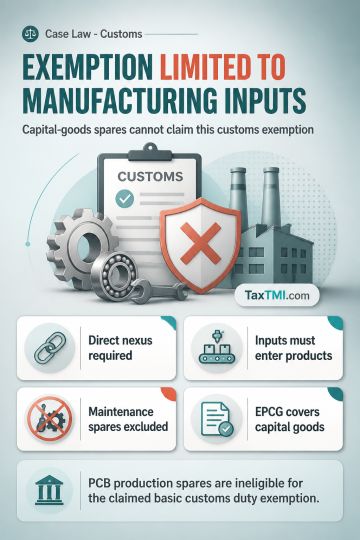
Notification No. 24/2005-Cus. requires a direct nexus between the imported goods and manufacture of the specified final products for exemption under Sl. No. 39. Read harmoniously, the entry covers consumables, raw materials, components and inputs consumed in or incorporated into final products; it does not extend to capital goods, machinery, accessories or replacement spares used to maintain production equipment. Separate notification entries and the EPCG scheme address capital goods. Decisions under differently worded notifications or schemes do not govern this interpretation. Accordingly, spare parts for capital goods used to manufacture printed circuit boards are not eligible for the claimed basic customs duty exemption.
Notification No. 24/2005-Cus. requires a direct nexus between the imported goods and manufacture of the specified final products for exemption under Sl. No. 39. Read harmoniously, the entry covers consumables, raw materials, components and inputs consumed in or incorporated into final products; it does not extend to capital goods, machinery, accessories or replacement spares used to maintain production equipment. Separate notification entries and the EPCG scheme address capital goods. Decisions under differently worded notifications or schemes do not govern this interpretation. Accordingly, spare parts for capital goods used to manufacture printed circuit boards are not eligible for the claimed basic customs duty exemption.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI