Faceless assessment and registration procedures are updated through electronic communication, revised recovery rules, extended deadlines, and replacem...
Risk-based selective vessel boarding requires accurate declarations and preserves master and agent liability where physical inspections are not select...
Permanent-establishment reassessment cannot revisit scrutinised disclosures; extended reopening fails without undisclosed material facts and within st...
A memorandum contemplating future finalisation of consideration...
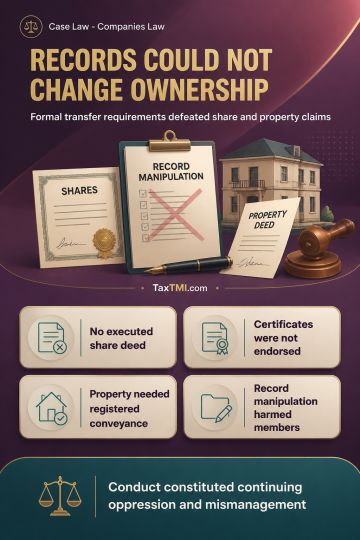
Statutory transfer formalities invalidated alleged share and property transfers, while retrospective record manipulation constituted oppression and mismanagement.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
A memorandum contemplating future finalisation of consideration and a subsequent share transfer did not complete a transfer of the company's shareholding. In the absence of an executed share transfer deed, endorsed share certificates and statutory compliance, later retrospective filings could not displace contemporaneous records showing the existing shareholders. Similarly, book entries against an unsecured interest-free loan could not transfer the company's immovable property without a registered conveyance, particularly where the alleged transferee continued paying rent. Retrospective manipulation of corporate records, attempted usurpation of shareholding and removal of the sole asset prejudiced members and constituted continuing oppression and mismanagement.
A memorandum contemplating future finalisation of consideration and a subsequent share transfer did not complete a transfer of the company's shareholding. In the absence of an executed share transfer deed, endorsed share certificates and statutory compliance, later retrospective filings could not displace contemporaneous records showing the existing shareholders. Similarly, book entries against an unsecured interest-free loan could not transfer the company's immovable property without a registered conveyance, particularly where the alleged transferee continued paying rent. Retrospective manipulation of corporate records, attempted usurpation of shareholding and removal of the sole asset prejudiced members and constituted continuing oppression and mismanagement.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI