Mandatory textile export qualifiers distinguish flame-retardant fabrics from other listed fabrics for automated identification under the textiles ince...
Personal liberty safeguards restrict arrest after court-directed GST appearance, requiring interim release where authorities overreach pending proceed...
Alternative statutory remedy and delay bar GST writ challenges despite pending rectification, while distinct subject matter permits parallel proceedin...
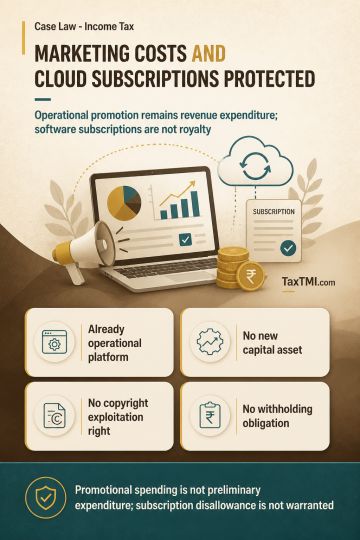
Marketing and advertising expenditure incurred to promote an already operational online streaming platform is described as revenue expenditure where it supports business expansion and user engagement without creating a new capital asset or advantage in the capital field. The notes state that the enduring-benefit test is not conclusive and that such expenditure cannot be treated as preliminary expenditure for amortisation. They also state that end-user payments to non-residents for subscription-based software and cloud services are not royalty absent a right to exploit underlying copyright or intellectual property; accordingly, no tax deduction at source obligation arises and related disallowance is not warranted.
Marketing and advertising expenditure incurred to promote an already operational online streaming platform is described as revenue expenditure where it supports business expansion and user engagement without creating a new capital asset or advantage in the capital field. The notes state that the enduring-benefit test is not conclusive and that such expenditure cannot be treated as preliminary expenditure for amortisation. They also state that end-user payments to non-residents for subscription-based software and cloud services are not royalty absent a right to exploit underlying copyright or intellectual property; accordingly, no tax deduction at source obligation arises and related disallowance is not warranted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI