Cross-border secondment reimbursements require separate employment and knowledge-transfer analysis before taxation as included services under the Indi...
Customs procedure uniformity requires adoption of model clearance practices, subject to specific local requirements and infrastructure or geographical...
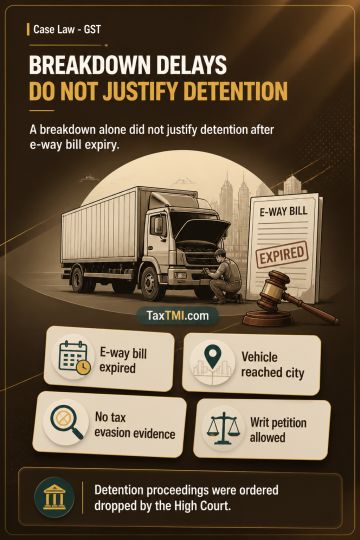
Expiry of an e-way bill alone did not justify detention where the vehicle reached the relevant city within the permitted period but could not complete the short remaining journey because of a breakdown. In the absence of any indication of tax evasion, treating the lapse as sufficient for detention was characterised as improper and hyper-technical. The High Court allowed the writ petition and directed that all proceedings arising from the detention be dropped.
Expiry of an e-way bill alone did not justify detention where the vehicle reached the relevant city within the permitted period but could not complete the short remaining journey because of a breakdown. In the absence of any indication of tax evasion, treating the lapse as sufficient for detention was characterised as improper and hyper-technical. The High Court allowed the writ petition and directed that all proceedings arising from the detention be dropped.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI


 Get Daily Updates