Faceless assessment and registration procedures are updated through electronic communication, revised recovery rules, extended deadlines, and replacem...
Risk-based selective vessel boarding requires accurate declarations and preserves master and agent liability where physical inspections are not select...
Permanent-establishment reassessment cannot revisit scrutinised disclosures; extended reopening fails without undisclosed material facts and within st...
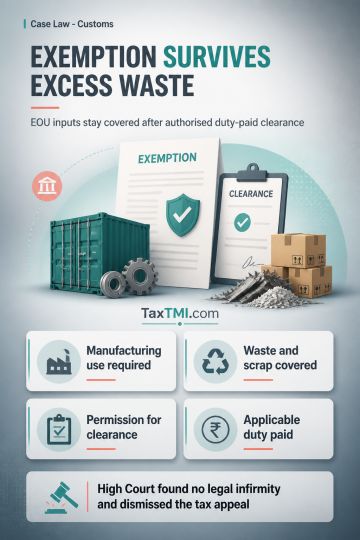
Customs exemption for imported inputs used by a 100% Export Oriented Unit extends under Notification No. 52/2003-Cus. to waste and scrap generated during manufacture. The controlling condition is that the imported goods are used to manufacture finished goods. Waste exceeding prescribed norms does not by itself defeat exemption where it is not removed without permission and is cleared on payment of applicable duty. The High Court found no legal infirmity in deletion of the customs-duty demand and dismissed the tax appeal, holding that no substantial question of law arose.
Customs exemption for imported inputs used by a 100% Export Oriented Unit extends under Notification No. 52/2003-Cus. to waste and scrap generated during manufacture. The controlling condition is that the imported goods are used to manufacture finished goods. Waste exceeding prescribed norms does not by itself defeat exemption where it is not removed without permission and is cleared on payment of applicable duty. The High Court found no legal infirmity in deletion of the customs-duty demand and dismissed the tax appeal, holding that no substantial question of law arose.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI