Residual food-preparation classification places fermented Nata De Coco outside fruit-jelly categories, changing its GST treatment across notified peri...
Settlement application eligibility requires a pending assessment when filed, preventing an extra prior-eligibility condition from blocking considerati...
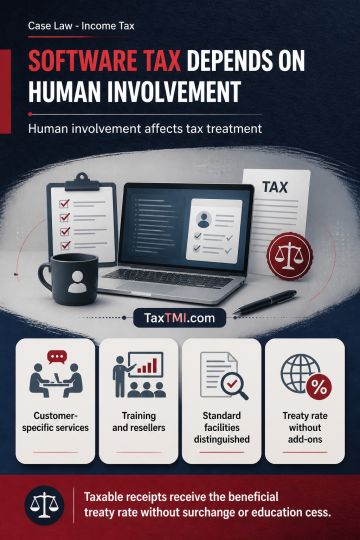
Taxability of receipts from non-customised software, SaaS and related services under the India-Ireland DTAA depends on whether automated facilities involve the requisite human element and constitute specialised services rather than standard facilities available to all users. The note distinguishes this fees-for-technical-services inquiry from software royalty analysis under the India-USA DTAA and identifies the need to examine customer-specific service delivery, training and reseller involvement. Where such receipts are taxable, the beneficial treaty rate applies without surcharge or education cess. It also addresses statutory interest on refunds and verification of TDS adjustment.
Taxability of receipts from non-customised software, SaaS and related services under the India-Ireland DTAA depends on whether automated facilities involve the requisite human element and constitute specialised services rather than standard facilities available to all users. The note distinguishes this fees-for-technical-services inquiry from software royalty analysis under the India-USA DTAA and identifies the need to examine customer-specific service delivery, training and reseller involvement. Where such receipts are taxable, the beneficial treaty rate applies without surcharge or education cess. It also addresses statutory interest on refunds and verification of TDS adjustment.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI