Residual food-preparation classification places fermented Nata De Coco outside fruit-jelly categories, changing its GST treatment across notified peri...
Settlement application eligibility requires a pending assessment when filed, preventing an extra prior-eligibility condition from blocking considerati...
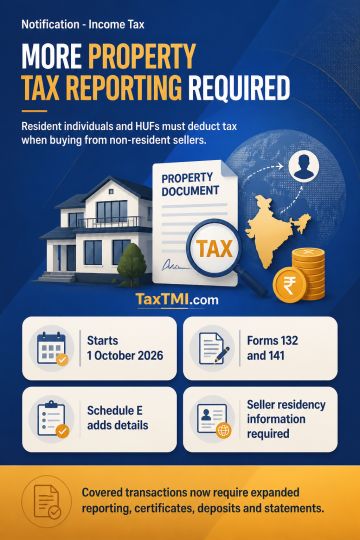
Effective 1 October 2026, the TDS compliance framework extends to consideration for transfer of immovable property where a resident individual or HUF must deduct tax under section 393(2). Rules 215, 218 and 219 now require the relevant TDS certificate, deposit and statement reporting for such transactions. Form 132 and Form 141 are amended to cover property transfers involving non-resident sellers and resident individual or HUF buyers. New Schedule E in Form 141 requires property, buyer, seller, consideration, instalment and tax-deduction details. Non-resident seller reporting requires contact details, overseas address, tax residency certificate and tax identification information, including where PAN is unavailable.
Effective 1 October 2026, the TDS compliance framework extends to consideration for transfer of immovable property where a resident individual or HUF must deduct tax under section 393(2). Rules 215, 218 and 219 now require the relevant TDS certificate, deposit and statement reporting for such transactions. Form 132 and Form 141 are amended to cover property transfers involving non-resident sellers and resident individual or HUF buyers. New Schedule E in Form 141 requires property, buyer, seller, consideration, instalment and tax-deduction details. Non-resident seller reporting requires contact details, overseas address, tax residency certificate and tax identification information, including where PAN is unavailable.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI