Residual food-preparation classification places fermented Nata De Coco outside fruit-jelly categories, changing its GST treatment across notified peri...
Settlement application eligibility requires a pending assessment when filed, preventing an extra prior-eligibility condition from blocking considerati...
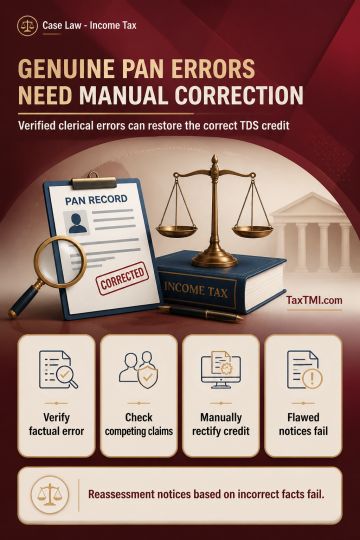
Incorrect entry of the purchaser's PAN in the seller's PAN field of Form 26QB can cause TDS credit to appear in the purchaser's Form 26AS. Where tax was deducted and deposited, correction of a bona fide clerical PAN error requires factual verification, including confirmation that no other person has claimed the corresponding credit, followed by manual rectification and consequential credit. The text also addresses reassessment initiated on an incorrect factual premise: treating a property purchase as a sale undermines the basis for the reassessment notice.
Incorrect entry of the purchaser's PAN in the seller's PAN field of Form 26QB can cause TDS credit to appear in the purchaser's Form 26AS. Where tax was deducted and deposited, correction of a bona fide clerical PAN error requires factual verification, including confirmation that no other person has claimed the corresponding credit, followed by manual rectification and consequential credit. The text also addresses reassessment initiated on an incorrect factual premise: treating a property purchase as a sale undermines the basis for the reassessment notice.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI