Residual food-preparation classification places fermented Nata De Coco outside fruit-jelly categories, changing its GST treatment across notified peri...
Settlement application eligibility requires a pending assessment when filed, preventing an extra prior-eligibility condition from blocking considerati...
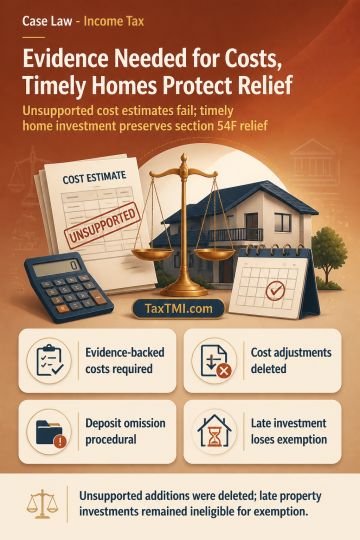
Unsupported estimation of indexed acquisition and construction or improvement costs cannot sustain capital-gains additions where neither the taxpayers' claims nor the Assessing Officer's adopted land and construction rates are supported by evidence. The reported tribunal decision deleted the resulting cost adjustments in all appeals. For section 54F, acquisition of a new residential property within the statutory period preserves the exemption despite non-deposit of interim unutilised gains in the Capital Gains Account Scheme, treating that omission as procedural. Exemption was allowed for investments made within time, but remained unavailable where the residential-property investment itself occurred beyond the prescribed period.
Unsupported estimation of indexed acquisition and construction or improvement costs cannot sustain capital-gains additions where neither the taxpayers' claims nor the Assessing Officer's adopted land and construction rates are supported by evidence. The reported tribunal decision deleted the resulting cost adjustments in all appeals. For section 54F, acquisition of a new residential property within the statutory period preserves the exemption despite non-deposit of interim unutilised gains in the Capital Gains Account Scheme, treating that omission as procedural. Exemption was allowed for investments made within time, but remained unavailable where the residential-property investment itself occurred beyond the prescribed period.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI