Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
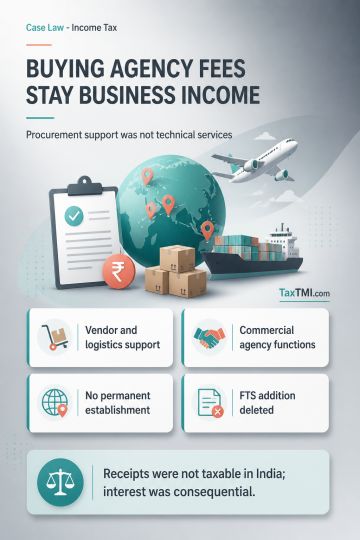
Under the retrospective amendment to sections 144C, 153 and 153B, the limitation periods under sections 153 and 153B apply only until the draft assessment order is forwarded. Thereafter, the Dispute Resolution Panel process and the Assessing Officer's finalisation operate under separate timelines, so a limitation objection to the final assessment order does not succeed. Buying agency services involving vendor identification, order placement, quality checks, logistics coordination and related procurement support are characterised as commercial agency functions rather than managerial, technical or consultancy services under Article 12(4) of the India-Switzerland DTAA. The resulting receipts remain business income and, absent a permanent establishment in India, are not taxable in India; the fees-for-technical-services addition is deleted, with interest consequential.
Under the retrospective amendment to sections 144C, 153 and 153B, the limitation periods under sections 153 and 153B apply only until the draft assessment order is forwarded. Thereafter, the Dispute Resolution Panel process and the Assessing Officer's finalisation operate under separate timelines, so a limitation objection to the final assessment order does not succeed. Buying agency services involving vendor identification, order placement, quality checks, logistics coordination and related procurement support are characterised as commercial agency functions rather than managerial, technical or consultancy services under Article 12(4) of the India-Switzerland DTAA. The resulting receipts remain business income and, absent a permanent establishment in India, are not taxable in India; the fees-for-technical-services addition is deleted, with interest consequential.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI