Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
Unreconciled jewellery found during a search may constitute...
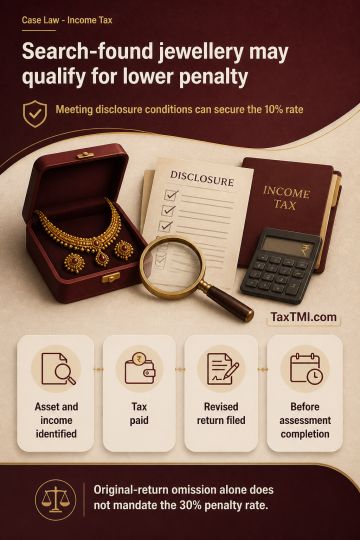
Concessional penalty for search-disclosed unreconciled jewellery applies where substantive disclosure conditions are met despite omission from original return.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Unreconciled jewellery found during a search may constitute undisclosed income where it cannot be matched with wealth-tax returns, valuation reports or contemporaneous records and is admitted as unrecorded income in a statement under section 132(4). A claim of acquisition in earlier years requires material establishing its source and period of acquisition. For income disclosed during search, the concessional 10% penalty rate under section 271AAB(1)(a) applies where the asset and income are specifically identified, tax is paid, and the income is included in a revised return before assessment completion. Omission from the original return does not automatically require the residuary 30% rate when substantive conditions for concessional treatment are met.
Unreconciled jewellery found during a search may constitute undisclosed income where it cannot be matched with wealth-tax returns, valuation reports or contemporaneous records and is admitted as unrecorded income in a statement under section 132(4). A claim of acquisition in earlier years requires material establishing its source and period of acquisition. For income disclosed during search, the concessional 10% penalty rate under section 271AAB(1)(a) applies where the asset and income are specifically identified, tax is paid, and the income is included in a revised return before assessment completion. Omission from the original return does not automatically require the residuary 30% rate when substantive conditions for concessional treatment are met.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI