Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
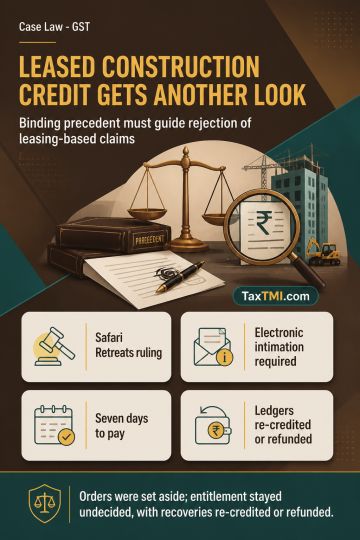
Input tax credit claims for construction intended to be leased or licensed require consideration of the principle that such construction is not undertaken on the taxable person's own account. Assessment findings rejecting a leasing-based claim without applying the Supreme Court ruling in Safari Retreats required fresh consideration; the assessment and consequential DRC-07 orders were set aside without deciding ITC entitlement on merits. Recovery by debiting electronic cash or credit ledgers also required prior electronic intimation in Form GST DRC-01D and seven days to pay under Rule 142B. Non-compliant recoveries were to be re-credited or refunded after the underlying assessments were set aside.
Input tax credit claims for construction intended to be leased or licensed require consideration of the principle that such construction is not undertaken on the taxable person's own account. Assessment findings rejecting a leasing-based claim without applying the Supreme Court ruling in Safari Retreats required fresh consideration; the assessment and consequential DRC-07 orders were set aside without deciding ITC entitlement on merits. Recovery by debiting electronic cash or credit ledgers also required prior electronic intimation in Form GST DRC-01D and seven days to pay under Rule 142B. Non-compliant recoveries were to be re-credited or refunded after the underlying assessments were set aside.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI