Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
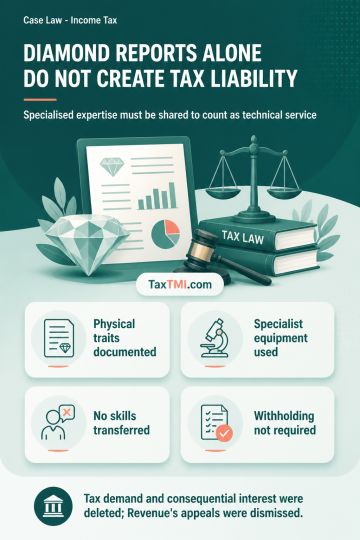
Diamond grading and certification charges for examining diamonds and issuing reports of their physical characteristics do not constitute fees for technical services merely because the provider uses specialised knowledge, equipment or qualified personnel. Where the service neither imparts managerial, technical or consultancy advice nor enables the recipient to perform diamond grading independently, the treaty "make available" condition is not met. Payments not chargeable to tax in India do not trigger withholding obligations on payments to non-residents. Accordingly, the demand for failure to deduct tax and consequential interest was deleted, and the Revenue's appeals were dismissed.
Diamond grading and certification charges for examining diamonds and issuing reports of their physical characteristics do not constitute fees for technical services merely because the provider uses specialised knowledge, equipment or qualified personnel. Where the service neither imparts managerial, technical or consultancy advice nor enables the recipient to perform diamond grading independently, the treaty "make available" condition is not met. Payments not chargeable to tax in India do not trigger withholding obligations on payments to non-residents. Accordingly, the demand for failure to deduct tax and consequential interest was deleted, and the Revenue's appeals were dismissed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI