Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
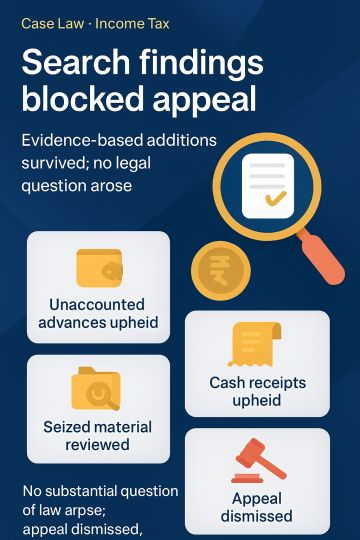
In a search assessment, additions for unaccounted advances and cash receipts were upheld on the basis of composite appellate orders and concurrent findings of fact drawn from seized material. The High Court held that the Commissioner (Appeals) and the Tribunal had considered the entire record across the relevant years, and the Tribunal's lack of separate elaborate reasoning for one year did not, by itself, justify remand. Because the dispute turned on appreciation of evidence and factual conclusions, no substantial question of law arose under Section 260A, and the appeal was dismissed.
In a search assessment, additions for unaccounted advances and cash receipts were upheld on the basis of composite appellate orders and concurrent findings of fact drawn from seized material. The High Court held that the Commissioner (Appeals) and the Tribunal had considered the entire record across the relevant years, and the Tribunal's lack of separate elaborate reasoning for one year did not, by itself, justify remand. Because the dispute turned on appreciation of evidence and factual conclusions, no substantial question of law arose under Section 260A, and the appeal was dismissed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI