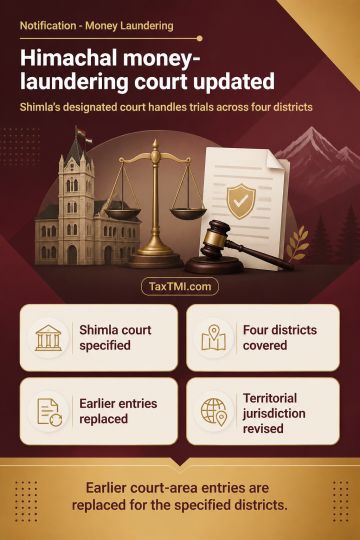
Territorial jurisdiction for money-laundering trials is revised for specified districts, replacing earlier court-area entries under the statutory fram...
Regular bail was refused in allegations of fraudulent availment and utilisation of input tax credit on fake invoices because the investigation was still at a crucial stage and the alleged fraud was of significant magnitude. The Court held that parity decisions cited by the petitioners did not assist, as the facts were different and their custody period was shorter. The medical condition of a relative was also found insufficient to justify release at that stage. The criminal petitions were dismissed.
Regular bail was refused in allegations of fraudulent availment and utilisation of input tax credit on fake invoices because the investigation was still at a crucial stage and the alleged fraud was of significant magnitude. The Court held that parity decisions cited by the petitioners did not assist, as the facts were different and their custody period was shorter. The medical condition of a relative was also found insufficient to justify release at that stage. The criminal petitions were dismissed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI