 TaxTMI





 19 Nov 2026

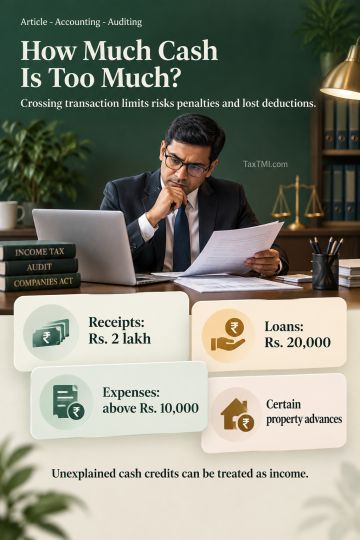
Cash feels quick, simple and private. Under modern tax law it is increasingly visible, expensive and risky - and clients often learn that only at assessment.
On the evening of 8 November 2016, India announced that Rs. 500 and Rs. 1,000 notes - about 86% of currency in circulation by value - would stop being legal tender at midnight.
Over the following months banks received deposits of old notes on a vast scale; the Reserve Bank of India later reported that around 99% of the demonetised currency came back into the banking system.
Economists still argue about demonetisation's costs and benefits. One consequence, though, was clear for every business: cash that had been invisible suddenly needed explaining. Authorities analysed deposits, and many depositors were asked about the source of their money.
"Sir, payment will be in cash"
Every Indian business has heard it; some owners have said it. Cash feels convenient - no bank charges, instant settlement, fewer questions.
Yet over ten years the statute has kept tightening the screws on big cash dealings, and UPI has made paying digitally quicker and cheaper than handing over notes. Cash convenience now carries a legal price.
Lesson from history: money without a trail
For most of history, coins and notes let strangers trade without records - that was their strength, and also why every revenue-hungry state eventually sought ways to see transactions, through markets, tolls, registers and now banking data.
The direction has been consistent: as economies formalise, room for invisible money shrinks. Businesses that move with that trend carry less risk; those that resist carry more.
Why the law targets cash
Cash is hard to trace, which makes it easier to:
- Under-report income.
- Bring unaccounted money into the books disguised as loans or capital.
- Inflate expenses through fictitious payments.
To discourage this, tax law imposes restrictions and consequences on cash. These rules carried forward when the Income-tax Act, 2025 replaced the 1961 Act from 1 April 2026, albeit with new section numbers. Verify current thresholds before relying on them.
The Three Cash Lines
Three numbers to remember - the Three Cash Lines.
Line 1: Rs. 2 lakh - receipts
The law generally prohibits receiving cash of Rs. 2 lakh or more:
- from one person in a day,
- for a single transaction, or
- for transactions relating to one event or occasion,
subject to specified exceptions. The penalty has been equal to the cash received - take Rs. 5 lakh in cash for a sale and the penalty can be Rs. 5 lakh.
Line 2: Rs. 20,000 - loans
Taking or returning loans, deposits and some property-related advances in cash of Rs. 20,000 or more is barred (conditions and exceptions apply), and the penalty tracks the sum involved. It catches many small businesses that take or repay "hand loans" from friends or relatives in cash.
Line 3: Rs. 10,000 - expenses
Where a client pays a single person more than Rs. 10,000 in cash on one day, the expense is ordinarily not allowed as a deduction (transporters hired for vehicles get a higher ceiling, and some exceptions exist). The expense is real, yet tax is paid as if it never happened.
In a nutshell
Essence: receipts stop at Rs. 2 lakh, loans at Rs. 20,000, expenses at Rs. 10,000 - breach any of them in cash and the tax bill quickly outweighs the convenience.
Two further dangers
Unexplained cash credits
If cash credits or deposits appear in the books and their nature and source - including the identity and creditworthiness of the person providing the money - can't be satisfactorily explained, they can be treated as income. Such income has been taxed at a high special rate, with surcharge and possible penalties, and without normal deductions.
High-value transaction reporting
Banks, sub-registrars, fund houses and other reporting entities file details of large transactions, and these flow into each taxpayer's AIS. When those reported figures do not square with the return, an enquiry is the usual result.
Cash no longer disappears. Someone else's report simply captures it.
Traps practitioners see repeatedly
- A trader accepts Rs. 3 lakh in cash for one invoice, split into "three bills." Splitting a single transaction doesn't avoid the rule.
- A small company takes Rs. 50,000 in cash from a director as a temporary loan.
- Contract labour or transport is paid in cash above the limits without considering disallowance.
- Cash sales are banked weeks later in lump sums that don't match sales records.
- A property deal includes part cash consideration.
The uncomfortable reality
Some businesses still believe cash "saves tax." In practice, large cash dealings often:
- Invite a penalty as large as the cash itself.
- Push up taxable profit because expenses get disallowed.
- Leave credits nobody can explain, taxed at a punishing special rate.
- Undermine how lenders and auditors view the accounts.
The tax saved through cash is usually far smaller than the tax risk it creates.
For practitioners: what to check and advise
- Scan the cash book each quarter. Flag receipts, loans and payments approaching or crossing the three lines before year-end, when they can still be addressed.
- Use tax audit reporting as a control. Cash receipts, loans and payments feature in tax audit disclosures where applicable; review them early rather than at the reporting deadline.
- Reconcile AIS with the books. Compare reported cash deposits and high-value transactions with recorded sales and explain differences before filing.
- Document the source of every credit. For loans and capital, keep confirmations, bank trails and lender identity documents on file.
- Recommend internal limits. Help clients set approval thresholds well below the legal lines and train front-desk staff accordingly.
Building a low-cash business
1. Make digital the default - UPI, cards, net banking and payment links are cheap for most merchants and leave clean records.
2. Set internal limits below legal ones - for example, owner approval for any cash receipt above Rs. 50,000 or cash payment above Rs. 5,000.
3. Record and bank daily - every cash sale invoiced and deposits matching sales.
4. Route every loan through the bank - borrowings, capital and advances move only by banking channels, backed by paperwork.
5. Coach counter staff to turn down big cash offers courteously and say why.
6. Sit with the accountant every month to go through the cash book.
Indicators of success
- Cash falls as a share of total receipts and payments.
- No transactions exceed legal cash limits.
- Book cash matches physical cash.
- Digital options are offered to every customer and supplier.
- Banking relationships improve as flows become traceable.
Outlook: the coming decade
With UPI, e-invoices and shared banking data, cash is becoming easier to spot and less needed, and analytics flag cash-heavy profiles almost automatically. Small daily cash will remain lawful, but a business built on it will struggle to scale, raise finance or stand behind its accounts.
Immediate actions by role
- Owner: list every cash transaction above Rs. 10,000 in the last three months.
- Accountant: test them against the legal limits.
- Sales: offer UPI and payment links to every customer.
- Purchasing: move cash-paid suppliers to bank transfers.
Illustration from a smaller enterprise
Take an illustrative building-materials dealer who accepts large cash payments from contractors. An assessment finds several receipts above the single-transaction limit, and the penalty equals the amount received.
He switches every contractor sale above the limit to UPI or bank transfer and offers a small discount for immediate digital payment. Collections speed up, records get cleaner and the penalty risk disappears.
The objection we hear most - and our response
The objection: "Many customers - farmers, small traders, rural buyers - still prefer cash. Refuse it and we lose business."
The answer: Cash isn't illegal, and many small transactions will stay in cash for years. The rules target large transactions and unrecorded ones. Clients can accept cash within the limits, record every rupee, bank it promptly and offer digital options that are now available almost everywhere. What they can't safely do is accept large sums, split invoices or keep cash off the books. Serve cash customers - just keep cash inside the law and inside the ledger.
Practitioners' FAQ
"Does the Rs. 2 lakh rule cover payments or only receipts?"
It restricts receipts. Payments are governed by other rules - the Rs. 10,000 expense disallowance and the Rs. 20,000 loan rule, for example.
"Can a large sale be split over several days?"
If the receipts relate to a single transaction or event, the aggregate generally counts; splitting doesn't avoid the rule.
"Are there exceptions?"
Yes - certain receipts by governments and banks and some specified situations. Check carefully before relying on any exception.
Position as at October 2026: These cash rules continue under the Income-tax Act, 2025 (in force from 1 April 2026) with new section numbers; the annual information statement and statement of financial transactions continue to report high-value transactions. Thresholds can be revised by Finance Acts - verify before relying on any figure in this article.
The international picture
Several jurisdictions put a ceiling on cash payments or demand that large cash dealings be reported, and anti-money-laundering rules target large cash dealings in property, jewellery and vehicles. The global direction is the same: more transparency, less anonymous cash.
Pitfalls
- Splitting invoices to stay under limits.
- Cash loans from relatives or friends.
- Large unexplained cash deposits.
- Cash payments to vendors "for a better price."
- Assuming small businesses aren't monitored.
Terms explained
- Cash limit - the maximum the tax law allows to be received or paid in cash for certain transactions.
- Digital trail - records created automatically by banking and payment systems.
- Penalty equal to the amount - a penalty matching the cash received in breach of limits.
Half-hour action exercise
From last quarter's cash book, mark:
1. Cash of Rs. 2 lakh or above received from a single party for one deal or occasion.
2. Cash loans or deposits of Rs. 20,000 or above, whether taken or returned.
3. Cash paid to one person exceeding Rs. 10,000 on a single day.
4. Cash banked that cannot be tied back to recorded cash sales.
Consult the adviser on each mark now - and change the process so it doesn't recur.
Summary for busy professionals
- Demonetisation in 2016 showed how quickly cash may need explaining; reporting systems now make large cash dealings visible.
- The Three Cash Lines - Rs. 2 lakh receipts Rs. 20,000 loans Rs. 10,000 expenses - continue under the Income-tax Act, 2025.
- Unexplained cash credits can be taxed at high special rates; splitting doesn't avoid the rules.
- Default to digital, keep internal ceilings, deposit daily, keep loans off cash and review the cash book monthly.
- Cash customers can still be served - inside the limits and inside the books.
A traceable payment is the client's best witness when questions come.
References
- Reserve Bank of India, Annual Report 2017-18 - on the return of specified bank notes after demonetisation. rbi.org.in
- Ministry of Finance, Government of India - notification on specified bank notes (8 November 2016).
- Income-tax Act, 2025 (India) - provisions on cash receipts, cash loans, cash expenditure and unexplained credits. incometax.gov.in
- Income Tax Department - Annual Information Statement guidance. incometax.gov.in