 TaxTMI
 TaxTMI







 29 Oct 2026

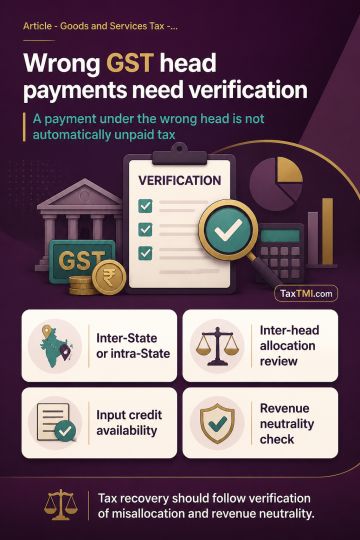
It is observed that despite 529 orders of GSTAT being available in the public domain, there is no change in the mindset of the audit team as well adjudication officers in Tamil Nadu. The lack of awareness amongst all concerned leads to payment of GST which is really unwarranted. Let us forget whatever happened till date, but things can -not continue like this for ever. Today is the most appropriate day to make a big as well as final full stop on one issue which is related to section 77(2) of the CGST Act as well as section 19(2) of the IGST Act which we shall examine in such a manner that whomsoever happens to read this article is relived from the burden of at least one issue.
It is pertinent to note that the GST law must be understood in full and not in a manner in which six blind persons see and describe how a big elephant is like. Exactly like a similar way, tax officials look only two sub-sections as below without observing the exact requirement under law. Sub section 2 of section 19 of IGST Act reads as "(2) A registered person who has paid central tax and State tax or Union territory tax, as the case may be, on a transaction considered by him to be an intra-State supply, but which is subsequently held to be an inter-State supply, shall not be required to pay any interest on the amount of integrated tax payable". Sub section 2 of section 77 of the CGST Act reads as "(2) A registered person who has paid integrated tax on a transaction considered by him to be an inter-State supply, but which is subsequently held to be an intra-State supply, shall not be required to pay any interest on the amount of Central tax and State tax or, as the case may be, the Central tax and the Union territory tax payable". Thus it is abundantly clear that the legislature has visualised a situation of probable tax head mismatch due to inadvertent errors and accordingly on careful thought provided for waiver of interest on such transactions. It is understood by tax officials as only interest is exempt and applicable tax has to be paid and the taxpayer has to apply for refund on taxes which are paid on a wrong head. This issue was settled as early as in November 2024 itself by the Division Bench of the Kerala High Court in the matter of Rejimon P Alex as reported in 2024 (12) TMI 399 Kerala High Court wherein para 9 reads as:
"9. We find that on the facts in the instant case, the notice issued to the appellant, and the demand confirmed against him, were in proceedings initiated under Section 73 of the GST Act. The said provisions are attracted only when it appears to a proper officer that any tax has not been paid or short paid or erroneously refunded, or where input tax has been wrongly availed or utilised for any reason. The case before us clearly reveals that there has been no wrong availment of credit, and that the only mistake committed by the appellant was an inadvertent and technical one, where he had omitted to mention the IGST figures separately in Form GSTR 3A. The mistake was also insignificant because it is not in dispute that there was no outward supply attracting IGST that was effected by him. We therefore set aside the impugned judgment of the learned Single Judge and allow the Writ Petition by quashing Ext.P14 order and declaring that the appellant shall not be seen as having availed excess credit for the purposes of initiating proceedings under Section 73 of the GST Act".
Unlike the issue of single show cause notice for multiple financial years where we have contrary views, this issue is fully settled by the following few more endorsements by GSTAT during the recent past as described below.
| Case Reference | APL/34/BUR/2026 - 2026 (9) TMI 454 - GSTAT BENGALURU |
| Date of Order | 03/09/2026 |
| Operative Portion | Examine whether any part of the mismatch is the result of an inter-head misallocation between IGST and CGST/SGST. |
| Case Reference | APL/13/CHD/2026 - 2026 (10) TMI 1223 - GSTAT CHANDIGARH |
| Date of Order | 16/10/2026 |
| Operative Portion | 23. Regarding the demand of Rs. 1,52,088/- (IGST) on the second count, we are again of the view that the Appellant should be allowed the opportunity to demonstrate before the original adjudicating authority that there was no prejudice to, or loss of, revenue merely because they had deposited liability in the wrong head. The facts in this regard are, therefore, required to be verified by the original authority in this light, keeping in view the relevant legal provisions. |
| Case Reference | APL/36/LCK/2026 - 2026 (9) TMI 151 - GSTAT LUCKNOW
|
| Date of Order | 27/08/2026 |
| Operative Portion | 8.3 We find that neither the Original Adjudicating Authority nor the First Appellate Authority has examined or verified whether the appellant had sufficient eligible ITC under the IGST head. The appellant's contention that the corresponding ITC was available under IGST but had been availed under the CGST and SGST heads, without availing the same under IGST, thereby rendering the matter revenue-neutral, has not been verified from the electronic credit ledger or returns filed by the appellant. |
Accordingly, it may be concluded that the issue has been demonstrated by four different orders of High Court as well as GSTAT benches. The tax officials all over India should not raise and demand under 73/74/74A as this is not a case of non-payment or short payment of GST. As this is only an issue to be settled based on the views expressed by courts after careful as well as critical examination of the issue in an exhaustive manner, CBIC may voluntarily issue necessary clarifications in this regard as payment under one head and seeking refund under a different head is a cumbersome as well as futile exercise for both taxpayer as well as tax officer. The Government has indicated that they are willing to resolve genuine GST issues as is evident from recent happenings.