Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ Call / WhatsApp at: +91 99117 96707

For more information, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws---- ❯
  • ---- All Laws----
  • Income Tax
  • Direct Taxes
  • Benami Property
  • Central GST Laws
  • SGST - State GST Laws
  • Customs
  • FTP - Foreign Trade Policy
  • SEZ - Special Economic Zone
  • FEMA - Foreign Exchange Management
  • Companies Law
  • SEBI - Securities & Exchange Board of India
  • IBC - Insolvency and Bankruptcy
  • Law of Competition
  • PMLA - Money-Laundering
  • Indian Laws
  • Bill / Finance Bills
  • Wealth Tax
  • Service Tax
  • Central Excise
  • VAT / Sales Tax
Month:
---- All Months ---- ❯
  • ---- All Months ----
  • January
  • February
  • March
  • April
  • May
  • June
  • July
  • August
  • September
  • October
  • November
  • December
Year:
---- All Years ---- ❯
  • ---- All Years ----
  • 2026
  • 2025
  • 2024
  • 2023
  • 2022
  • 2021
  • 2020
  • 2019
  • 2018
  • 2017
  • 2016
  • 2015
  • 2014
  • 2013
  • 2012
  • 2011
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
☰   Show Results ❯
    Mechanical reassessment sanction requires independent application of mind; a bare endorsement can invalidate the resulting reassessment.
    Transfer-pricing comparability requires functional alignment; delayed associated-enterprise receivables need separate LIBOR-based benchmarking, while ...
    Allotment-based property rights determine capital-gains holding periods and agreement-date stamp valuation for residential flat acquisitions
    Subcontract Profit Duplication Bars Separate Estimated Addition, While Unsupported Donations and Provident Fund Damages Remain Disallowable
    Extended reassessment limitation in search cases requires asset-linked escaped income, invalidating additions based only on unexplained money or expen...
    Enhanced tolerance band under section 43CA applies retrospectively, deleting qualifying deemed-sale additions while disputed stamp valuation requires ...
    Aircraft dry-lease rentals receive India-Ireland treaty protection where international-traffic rules apply and unnotified anti-abuse modifications can...
    Profit-element taxation of unrecorded property on-money limits assessment to income rather than gross cash payment.
    Excess managerial remuneration recovered by an employer may adjust later-year salary income without reopening the original salary assessment.
    PBDIT benchmarking addresses depreciation-driven comparability distortions, requiring recomputation alongside working-capital adjustment and statutory...
    Territorial jurisdiction in customs seizure disputes follows the place where seizure and provisional-release proceedings create the cause of action.
    Knowledge of illegal import activity is essential before facilitation can support Customs Act penalties for undervaluation.
    Customs transaction value rejection requires communicated reasonable doubt, while written reassessment acceptance preserves challenges to enhanced val...
    Section 123 presumption requires Customs to establish foreign origin before gold confiscation or penalties can follow.
    Compulsory share buy-outs require prior oppression findings and current valuation, requiring reconsideration when statutory conditions are unmet.
    Operational Debt Proven by Tax Records and Ledger Balance Supports Insolvency Admission Despite Invoice PIN Error
    Deposited Funds: Withdrawal entitlement followed appeal party status, requiring remittance exclusively to the eligible appellant.
    Challenge-mechanism compliance clarifications permitted, while unilateral revised resolution plans may be refused under creditors' commercial discreti...
    FERA evidentiary proof: doubtful recovery, inadmissible loose sheets and uncorroborated retractions cannot sustain penalties or confiscation.
    Joint development service-tax treatment requires contractual analysis, while reverse-charge demands need proof of qualifying services and providers.
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Highlights
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries

Highlights

Back

All Highlights

Showing Results for :
Reset Filters
No Records Found

Highlights

Back

All Highlights

Judicial review of the administrative write-down must assess...

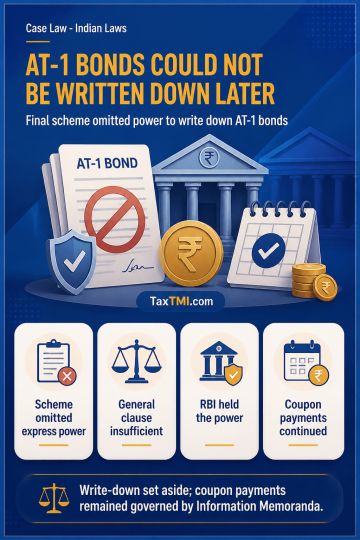
Administrative write-down authority cannot be implied after a reconstruction scheme omits specific AT-1 bond powers.

Contents
Summary
Note

Note

-

Bookmark

Print

Print

Indian Laws October 17, 2026 Case Laws SC
Judicial review of the administrative write-down must assess legality against the facts and law existing when it occurred; subsequent financial developments cannot alter that inquiry. Omission from the final Reconstruction Scheme of an express AT-1 bond write-down provision meant that a general savings clause could not imply authority for the Administrator to alter the bonds. The Master Circular required conversion or write-down before the Scheme took effect, and the power at the point of non-viability lay with RBI rather than an Administrator exercising board powers. The post-scheme write-down was therefore ultra vires, was set aside, and coupon payments remained governed by the Information Memoranda.

Topics

Acts Income Tax