Anti-profiteering obligations survive business demerger, complaint withdrawal, and customized supply arrangements where rate-reduction benefits are no...
Road restoration charges constitute taxable services when requested for commercial pipeline activity, requiring reverse-charge GST from the business r...
Interest on delayed release of requisitioned cash includes statutory pre-assessment interest and restitutionary compensation for unlawful post-assessm...
Incomplete inventory records justify rejecting accounts, while profit estimation requires relevant comparable material and interest falls under other ...
Transfer-pricing comparability requires functional alignment; delayed associated-enterprise receivables need separate LIBOR-based benchmarking, while ...
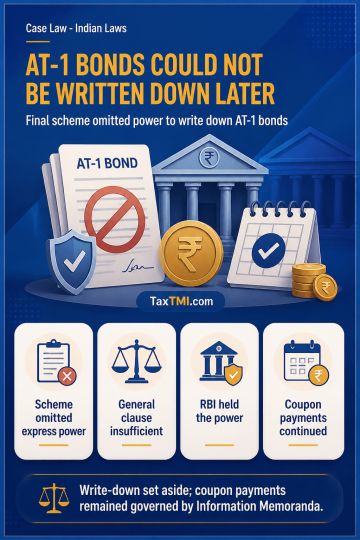
Judicial review of the administrative write-down must assess legality against the facts and law existing when it occurred; subsequent financial developments cannot alter that inquiry. Omission from the final Reconstruction Scheme of an express AT-1 bond write-down provision meant that a general savings clause could not imply authority for the Administrator to alter the bonds. The Master Circular required conversion or write-down before the Scheme took effect, and the power at the point of non-viability lay with RBI rather than an Administrator exercising board powers. The post-scheme write-down was therefore ultra vires, was set aside, and coupon payments remained governed by the Information Memoranda.
Judicial review of the administrative write-down must assess legality against the facts and law existing when it occurred; subsequent financial developments cannot alter that inquiry. Omission from the final Reconstruction Scheme of an express AT-1 bond write-down provision meant that a general savings clause could not imply authority for the Administrator to alter the bonds. The Master Circular required conversion or write-down before the Scheme took effect, and the power at the point of non-viability lay with RBI rather than an Administrator exercising board powers. The post-scheme write-down was therefore ultra vires, was set aside, and coupon payments remained governed by the Information Memoranda.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4912