Delayed judgment pronouncement alone does not invalidate Tribunal orders, while rectification cannot reopen evidence or negate confiscation-related pe...
Agricultural-land reinvestment qualifies when transfer consideration precedes replacement purchase, while unexamined claims may be reassessed on escap...
Bona fide public fixed-deposit explanations prevent concealment penalties where unexplained-credit additions lack independent evidence of undisclosed ...
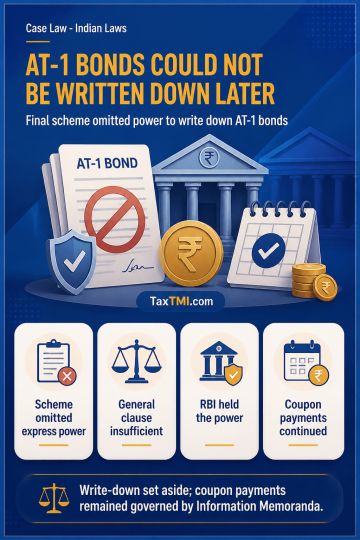
Judicial review of the administrative write-down must assess legality against the facts and law existing when it occurred; subsequent financial developments cannot alter that inquiry. Omission from the final Reconstruction Scheme of an express AT-1 bond write-down provision meant that a general savings clause could not imply authority for the Administrator to alter the bonds. The Master Circular required conversion or write-down before the Scheme took effect, and the power at the point of non-viability lay with RBI rather than an Administrator exercising board powers. The post-scheme write-down was therefore ultra vires, was set aside, and coupon payments remained governed by the Information Memoranda.
Judicial review of the administrative write-down must assess legality against the facts and law existing when it occurred; subsequent financial developments cannot alter that inquiry. Omission from the final Reconstruction Scheme of an express AT-1 bond write-down provision meant that a general savings clause could not imply authority for the Administrator to alter the bonds. The Master Circular required conversion or write-down before the Scheme took effect, and the power at the point of non-viability lay with RBI rather than an Administrator exercising board powers. The post-scheme write-down was therefore ultra vires, was set aside, and coupon payments remained governed by the Information Memoranda.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915