Clubbing of income from gifted property failed where the claim surfaced after reassessment limitation, sustaining capital-gains assessment in spouse's...
Employee stock-option discount qualifies as revenue expenditure, while royalty and service comparables require reliable functional and transactional b...
Page of 4902
Press 'Enter' after typing page number.
121 to 140 of 98021 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
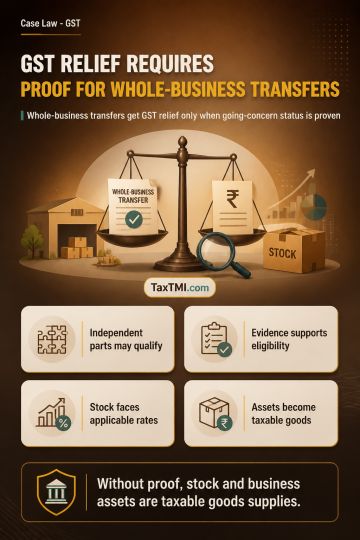
Transfer of an entire partnership business to a company without consideration may fall within GST supply, notwithstanding its occurrence outside the ordinary course of business. A transfer of a business undertaking as a going concern is classified as a supply of services rather than goods. The going-concern exemption applies only where the business, as a whole or independent part, satisfies that factual condition, requiring supporting evidence. If it does not qualify, the going-concern exception is unavailable and transferred stock and business assets are treated as taxable supplies of goods on cessation, at applicable rates.
Transfer of an entire partnership business to a company without consideration may fall within GST supply, notwithstanding its occurrence outside the ordinary course of business. A transfer of a business undertaking as a going concern is classified as a supply of services rather than goods. The going-concern exemption applies only where the business, as a whole or independent part, satisfies that factual condition, requiring supporting evidence. If it does not qualify, the going-concern exception is unavailable and transferred stock and business assets are treated as taxable supplies of goods on cessation, at applicable rates.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4902