Faceless assessment safeguards require requested personal hearings and adequate final show-cause response time, failing which reassessment is required...
Embezzlement losses in charitable institutions remain allowable when misappropriation is established, irrecoverable, and not a specified-person benefi...
National long-distance undertaking status supports deduction where separately licensed infrastructure, resources, revenue, and expenditure establish c...
Agency reimbursement income follows contractual deposit-liability computation, while pending deposit collections do not constitute deemed-dividend loa...
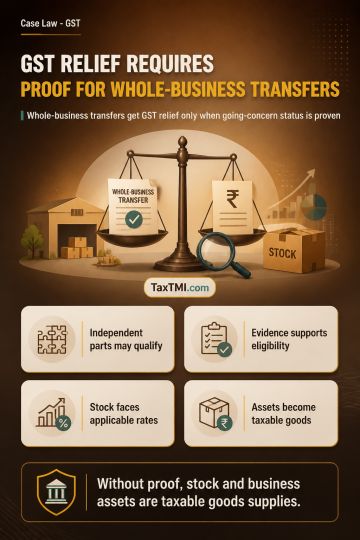
Transfer of an entire partnership business to a company without consideration may fall within GST supply, notwithstanding its occurrence outside the ordinary course of business. A transfer of a business undertaking as a going concern is classified as a supply of services rather than goods. The going-concern exemption applies only where the business, as a whole or independent part, satisfies that factual condition, requiring supporting evidence. If it does not qualify, the going-concern exception is unavailable and transferred stock and business assets are treated as taxable supplies of goods on cessation, at applicable rates.
Transfer of an entire partnership business to a company without consideration may fall within GST supply, notwithstanding its occurrence outside the ordinary course of business. A transfer of a business undertaking as a going concern is classified as a supply of services rather than goods. The going-concern exemption applies only where the business, as a whole or independent part, satisfies that factual condition, requiring supporting evidence. If it does not qualify, the going-concern exception is unavailable and transferred stock and business assets are treated as taxable supplies of goods on cessation, at applicable rates.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916