Blocked input tax credit for resort construction remains unavailable; interest follows actual utilisation, while delayed payment attracts statutory pe...
Duplicate PAN allocation requires record verification and deactivation reasons before assessment-related transactions can be attributed to an assessee...
Faceless assessment safeguards require requested personal hearings and adequate final show-cause response time, failing which reassessment is required...
Page of 4915
Press 'Enter' after typing page number.
681 to 700 of 98300 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
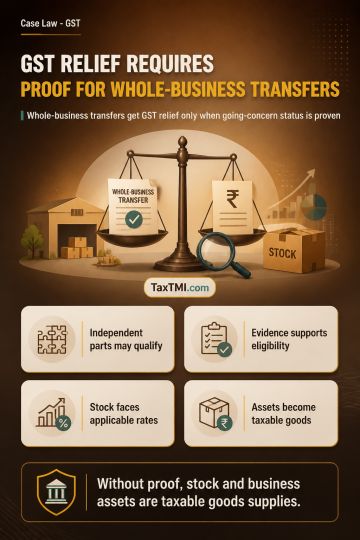
Transfer of an entire partnership business to a company without consideration may fall within GST supply, notwithstanding its occurrence outside the ordinary course of business. A transfer of a business undertaking as a going concern is classified as a supply of services rather than goods. The going-concern exemption applies only where the business, as a whole or independent part, satisfies that factual condition, requiring supporting evidence. If it does not qualify, the going-concern exception is unavailable and transferred stock and business assets are treated as taxable supplies of goods on cessation, at applicable rates.
Transfer of an entire partnership business to a company without consideration may fall within GST supply, notwithstanding its occurrence outside the ordinary course of business. A transfer of a business undertaking as a going concern is classified as a supply of services rather than goods. The going-concern exemption applies only where the business, as a whole or independent part, satisfies that factual condition, requiring supporting evidence. If it does not qualify, the going-concern exception is unavailable and transferred stock and business assets are treated as taxable supplies of goods on cessation, at applicable rates.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915